Finova Investor Digest
Global Indices, Currencies, Crypto & Commodities
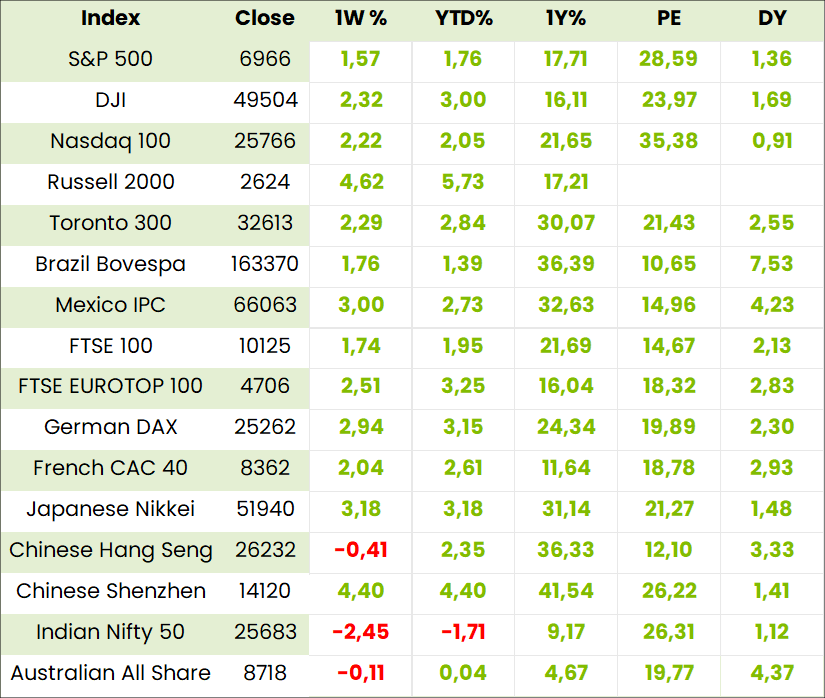

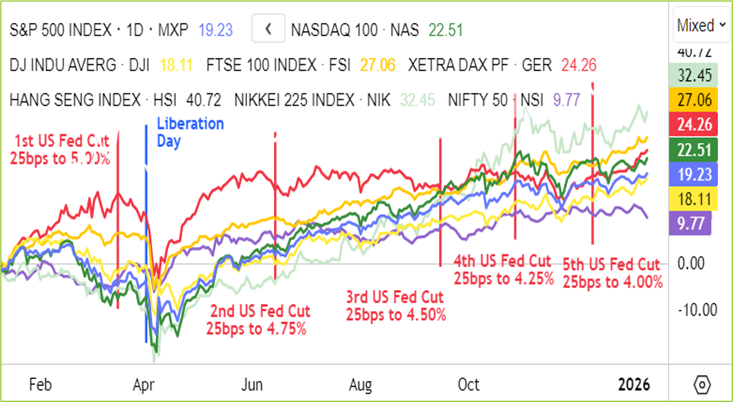
Global Indices 1 year to Date
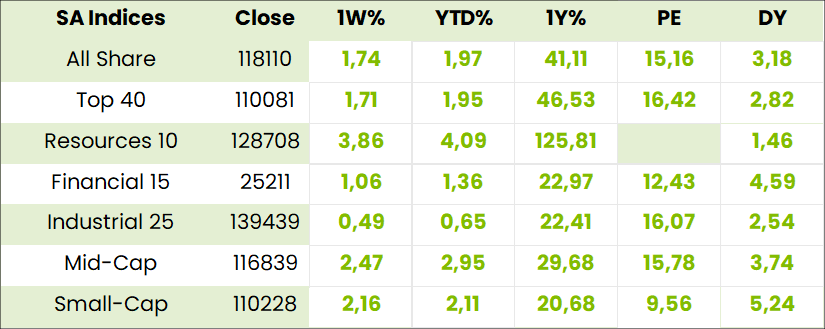
SA Indices

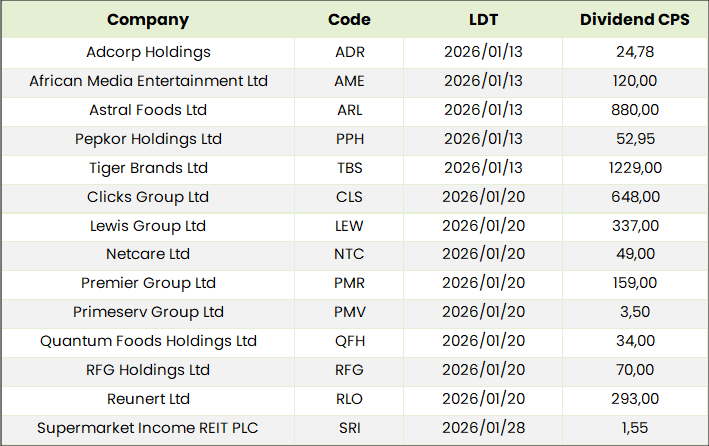
SA Upcoming Indicators & Dividends
SA Equity
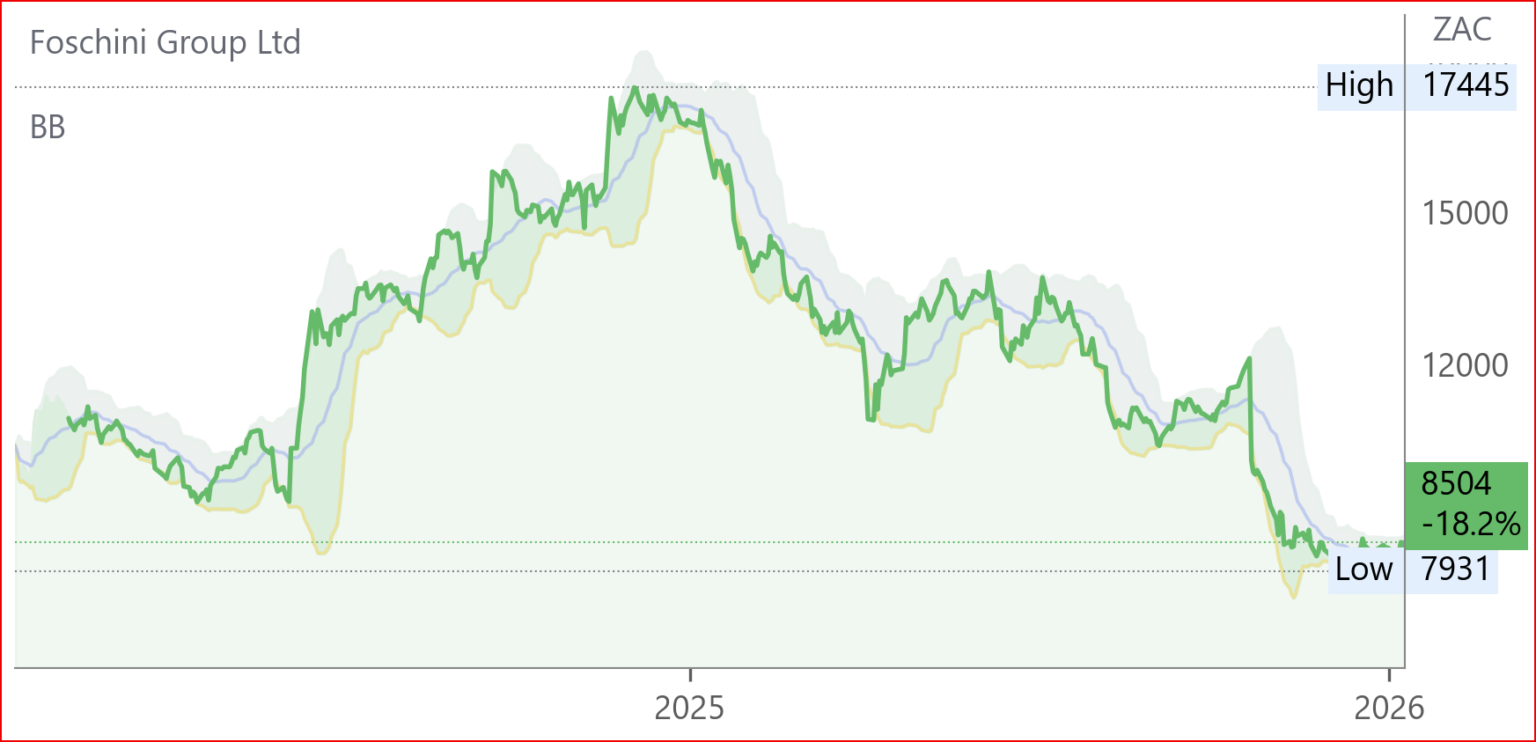
Foschini (TFG) Interim Results for 6M Sep ’25 (8504c)
HEPS: 292.6c (↓21.3% from 372c)
EPS: 290.8c (↓21.0% from 368c)
Operating Profit: R2.3bn (↓9.9% from R2.55bn)
Revenue: R31.4bn (↑12.2% from R28bn)
Gross Profit: R14.4bn (↑12.3% from R12.8bn)
Dividend: 130c interim (↓18.8% from 160c)
Revenue rose 12.2% to R31.4bn, supported by the White Stuff acquisition, while online sales surged 55.3% to contribute 14.7% of retail sales. Africa sales grew 5.3% with strong winter trade, though clearance markdowns pressured margins. London sales jumped 69% in GBP, largely from White Stuff, while Australia contracted 0.5%. EBIT fell 9.7% in Africa and 18.4% in Australia, reflecting negative operating leverage. Net debt increased R2.5bn due to acquisitions and buybacks. “While the first half has been difficult, the Group remains focused on operational resilience, prudent capital allocation, and leveraging its platform strengths and digital channels to drive growth.” – Anthony Thunström, CEO.
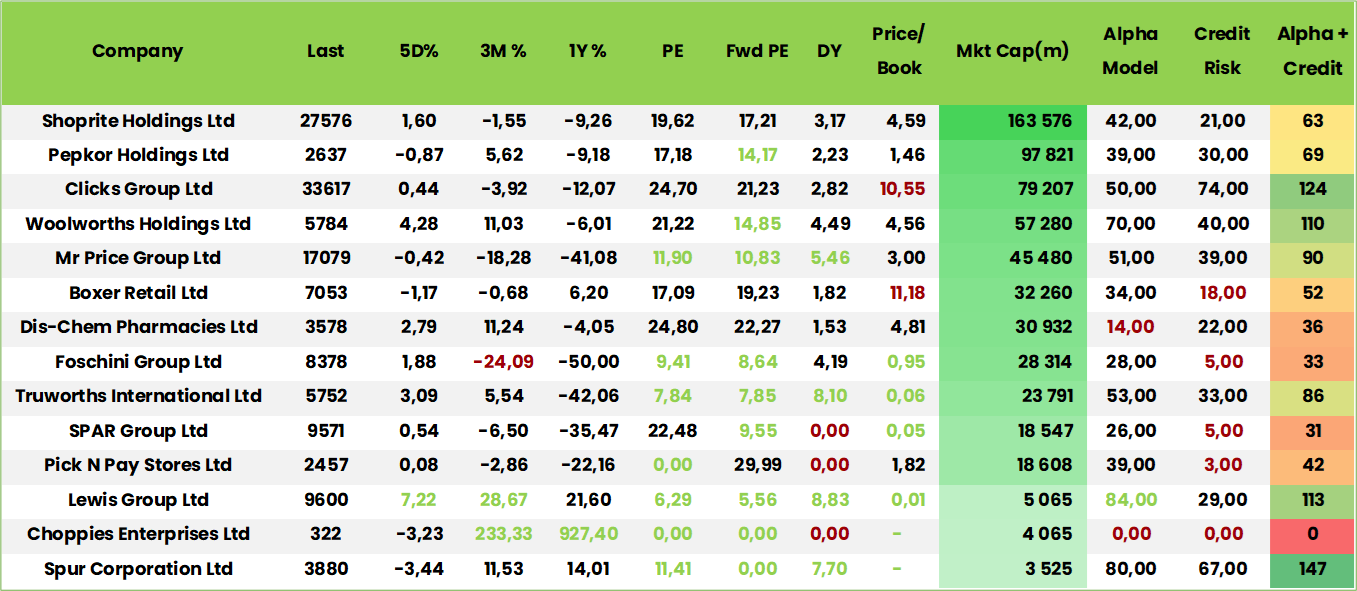
Comment: Having halved in price in just over a year since December 2024 the share price is some R10 lower than it was 10 years ago in January 2014. Nor is there much to suggest it will now reverse the “lost decade”. There was extraordinary volatility in consumer spending in 1H 26 and the online “Omnichannel” sales, which commenced in March 2023, are forecast to continue growing rapidly. Lower interest rates, a slight increase in GDP, and some filtering through of the precious metals boom to consumers will certainly make for some recovery in earnings and share price but real long term growth is another question.
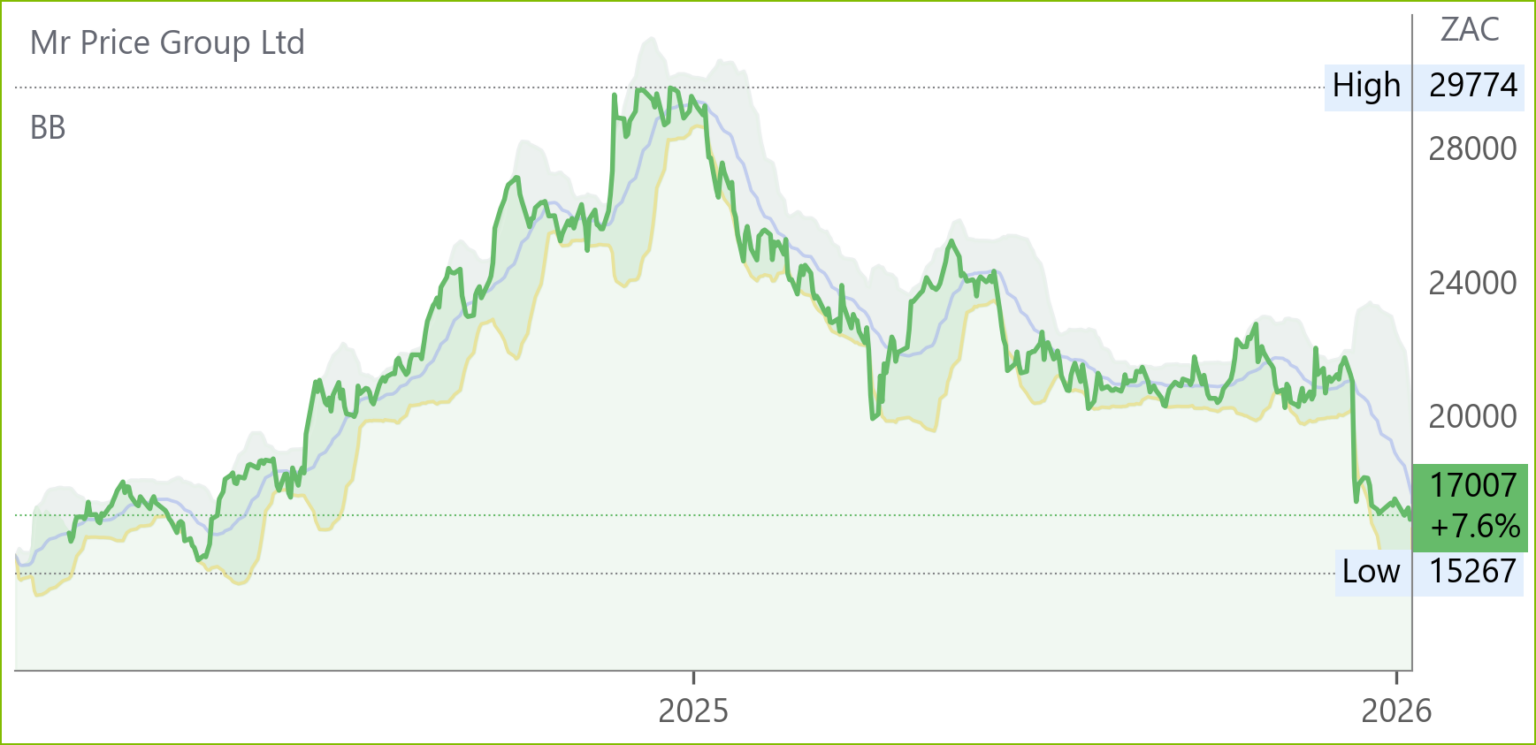
Mr Price (MRP) Interim Results for 26W Sep ’25 (17707c)
HEPS: 513.0c (↑6.5% from 482c)
EPS: 512.8c (↑6.5% from 481c)
Operating Profit: R2.1bn (↑5.7% from R1.99bn)
Revenue: R18.6bn (↑5.4% from R17.7bn)
Gross Profit: R7.4bn (↑6.2% from R6.97bn)
Dividend: 323.2c interim (↑6.5% from 303c)
Retail sales grew 5.5% to R17.8bn, supported by 91 new stores and online sales up 9.7%. Apparel gained over R200m in market share, with Power Fashion delivering its 14th consecutive quarter of gains. Homeware expanded GP margins despite a promotional market, while Telecoms surged 12.4% to R678m with 12 new stand-alone stores. Cash sales rose 5.6% and comprised 88.2% of retail sales. Inventory freshness remained healthy, with gross inventory up 4.5%.
The company finalised the purchase of NKD Group GmbH via its German subsidiary, though closing awaits regulatory approvals. Management reaffirmed NKD’s strategic fit and plans a capital markets event in Q1 ’26 to outline European value retail prospects. NKD’s FY24 audited results are filed in Germany, underscoring transparency and long‑term growth ambitions.
“I am pleased that we have once again executed our strategic intent of maximising sales growth at improved margins.” – Mark Blair, CEO.
Comment: having fallen 20% from 21463c on 3rd December Mr Price is likely to be offering value despite the understandably sceptical and knee jerk reaction of some investors to the announcement of the acquisition of 100 % of German retailer NKD. Starting way back with Old Mutual, Pick n Pay, Nampak, Woolworths and Spar the list of fruitless foreign forays goes on but, of course, there are successes such as OUTsurance, and, in recent years, REITS such Vukile in Spain and Portugal and others in the more rapidly growing economies East and Central Europe where is NKD is likely to continue expanding from its German base. Although David Blair gave an extensive rationale for the acquisition, he was precluded from giving the complete picture because NKD is in closed period. The Capital Markets Day will give a much fuller picture and investor concerns, especially around the acquisition price, can be thoroughly thrashed out. Such events can lead to substantial reassessment by the market as was the case with Sasol last year. Only when the full picture can be assessed, however, should investors take advantage of the current apparently low price level.
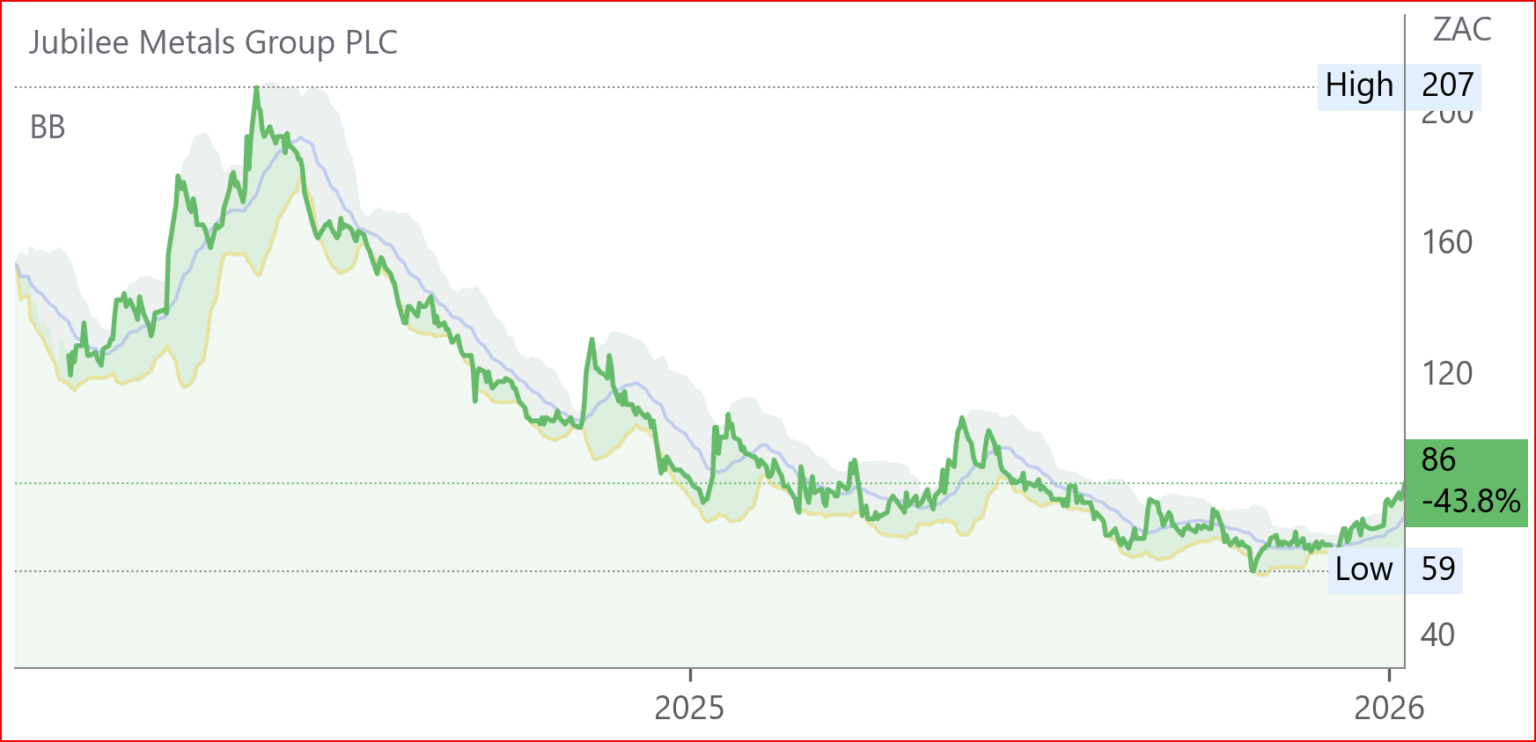
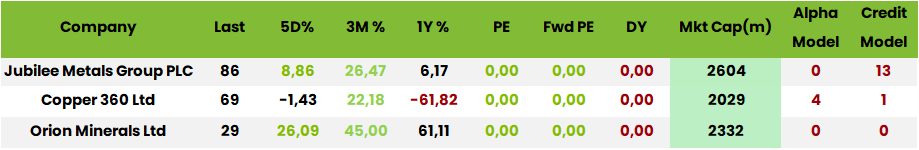
Jubilee Metals (JBL) Audited Results FY25 (86c)
HEPS: (0.62c) (↓ from 0.08c FY24)
EPS: (1.00c) (↓ from 0.21c FY24)
Operating profit: Loss (US$29.8m vs profit US$6.4m FY24)
Revenue: US$15.2m (↓17.9% from US$18.5m FY24, excl. deferred contracts)
Explanation: EPS fell sharply due to lower copper output during investment upgrades, while costs rose 81% per tonne.
Copper operations in Zambia were the focus, with major investment at Roan and Molefe Pit 2. Production rose 65% in Q1 FY26 to 938t, signalling recovery. Two copper sales contracts worth US$17.9m will be recognised in FY26. Chrome and PGM operations in South Africa are being disposed of by Dec ’25, positioning Jubilee as a pure-play copper producer. “The hard work in Zambia is beginning to show tangible results, and we remain focused, disciplined, and confident in our strategy.” – Leon Coetzer, CEO.
Comment: payment from the buyer of $90m (R1.49bn) for the SA chrome and Pgm operations is on track with receipt of $10m. Copper production of between 4500 and 5100t is expected for FY26 and while revenue of only $7421/t for FY06/25 was achieved against cost of $7776/t the latter was unusually high and LME prices for FY06/26 could easily be some 15% higher. Yes, Jubilee is now a pure-play copper producer” with substantial potential, using its proven SA chrome and pgms expertise to extract metal from its extensive holdings of more than a hundred years’ worth of copper mine dumps as well as waste rock and some small mining. The reality is that it is still very much in start-up (lossmaking for copper in FY25) mode with lots of negotiating ahead with suppliers anticipating copper boom type payments. At this stage, therefore, only small precautionary positions are justified.
Operating Updates & Trading Statements
Nepi Rockcastle (NRP) Pre‑Closing Update FY25 (14710c)
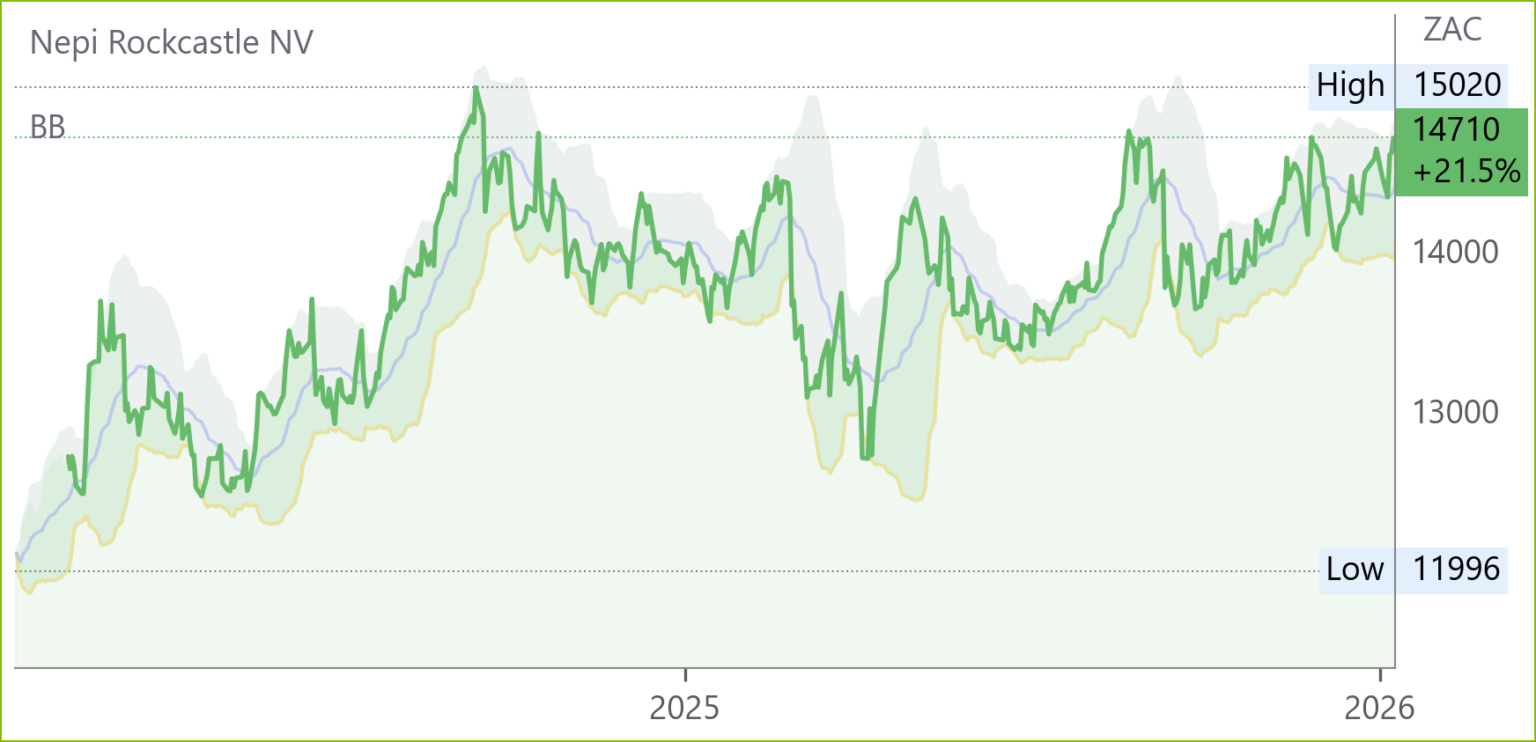
Business momentum strengthened with projected FY25 NOI up 11% y/y, supported by 2024 acquisitions, higher rents and near‑full occupancy (98.2% at Nov ’25). Tenant sales rose 3.7% LFL, while footfall dipped slightly. Renewable energy rollout advanced with Romania’s 54MW PV plant completed and 105MW projects due 2026–27. Liquidity reinforced by €740m undrawn RCFs and new green financing. “Our solid performance indicators support our confidence that we will continue to execute our successful business strategy for shareholders.” – Rüdiger Dany, CEO.

Snippets
Sanlam (SLM) confirmed MUFG Bank will invest USD 4.4bn for a 20% stake in Shriram Finance, diluting Sanlam’s effective holding to 7.6%. Regulatory progress allows Sanlam to raise stakes in Shriram General and Life Insurance, with a Piramal deal lifting SLIC to 68.41%. Transactions close Q1 ’26, reinforcing India as a core growth pillar.
Aspen (APN) agreed to sell its APAC operations (ex‑China) to BGH Capital for AUD 2.37bn (ZAR 26.5bn), valuing the unit at c.11x FY25 EBITDA. Proceeds will reduce debt, cut financing costs and sharpen focus on growth drivers including GLP‑1 launches, sterile manufacturing turnaround and vaccine commercialisation. Completion expected Q2 ’26, subject to approvals.
Jubilee (JBL) finalised the sale of its South African chrome and PGM operations to One Chrome, securing a US$10m cash instalment. Focus shifts to Zambian copper, with Tjate platinum retained for monetisation. CEO Leon Coetzer praised the SA team’s achievements and pledged to replicate success in copper: “I look forward to delivering significant growth.” – Leon Coetzer.
OUTsurance (OUT) announced its ordinary shares will gain a secondary listing on A2X from 14 January 2026. The primary JSE listing and issued share capital remain unchanged. A2X, regulated by the FSCA and Reserve Bank under the Financial Markets Act, provides an additional trading venue. Rand Merchant Bank acts as sponsor.
Glencore (GLN) confirms preliminary talks with Rio Tinto over a possible merger to create the world’s largest miner, likely via Rio acquiring Glencore through a court‑sanctioned scheme. No certainty exists on terms or structure. Rio must declare intent by 5 February 2026 under UK takeover rules. Disclosure obligations apply to major shareholders. The announcement contains inside information and confirms Glencore’s issued share capital.