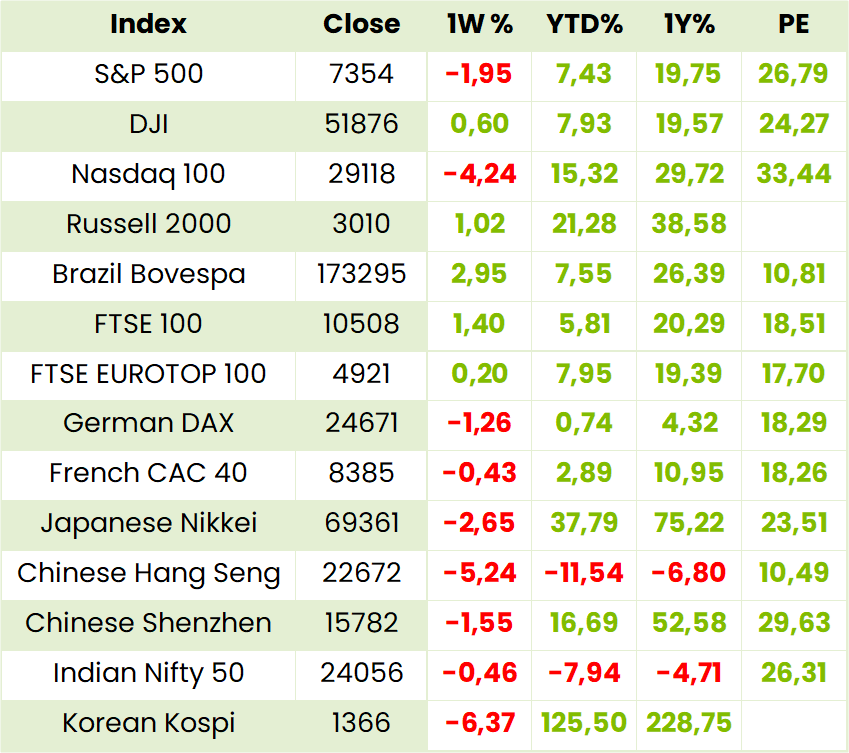
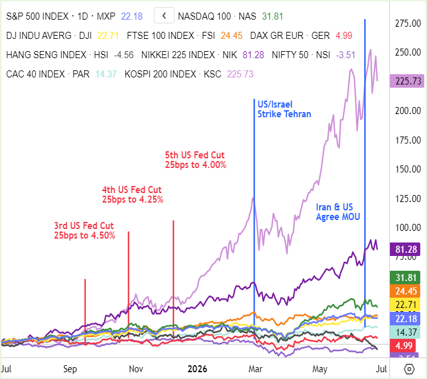
Global Indices
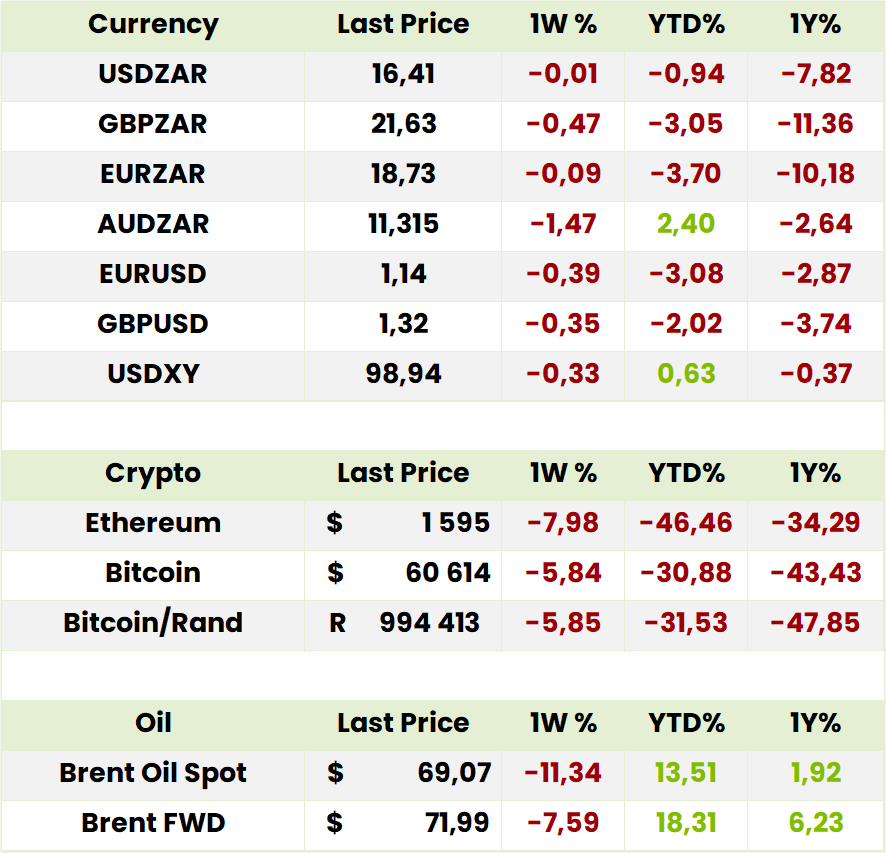
Currencies, Crypto & Commodities
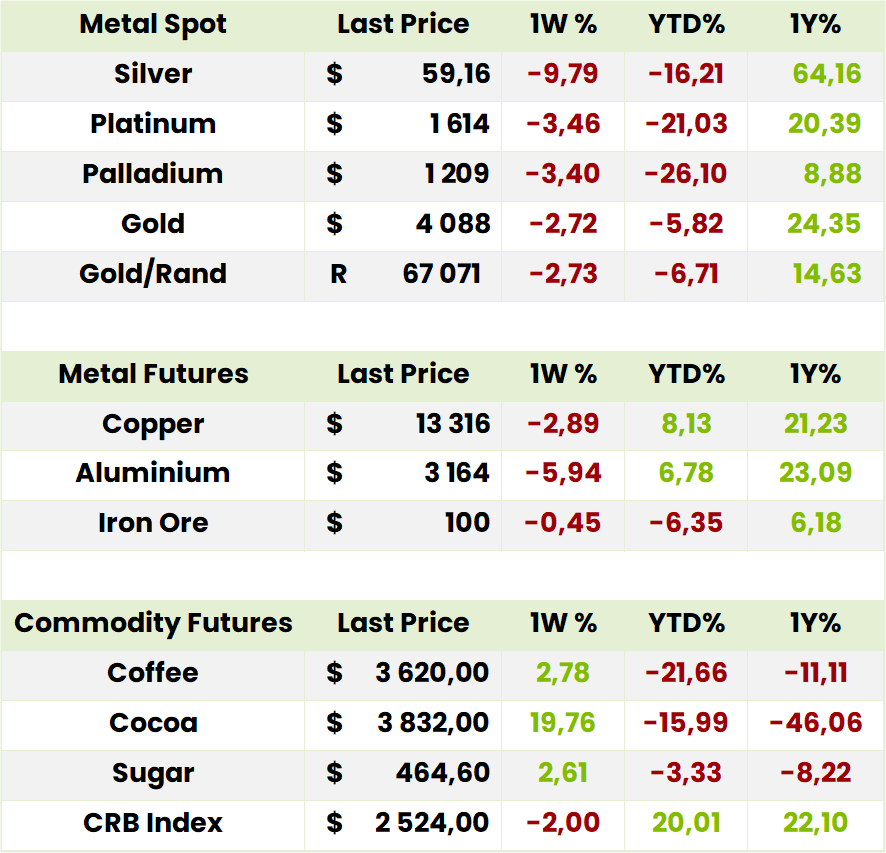
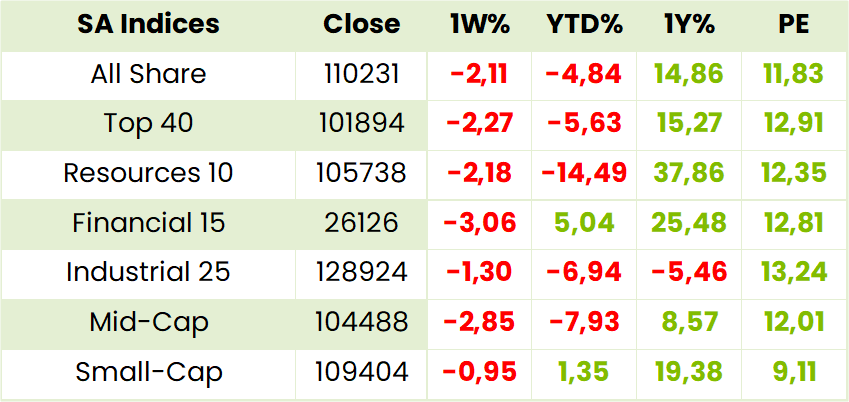
SA Indices

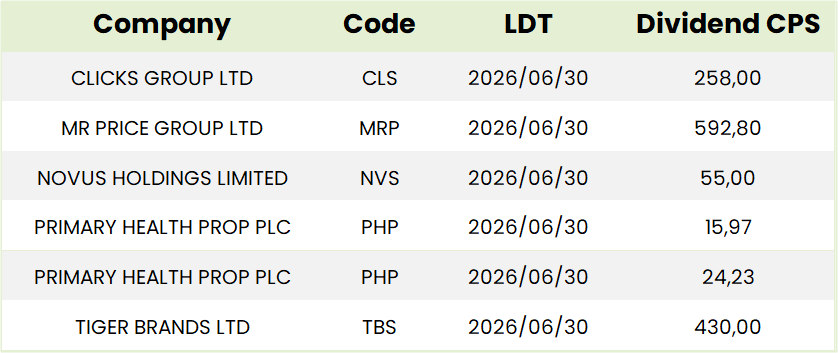
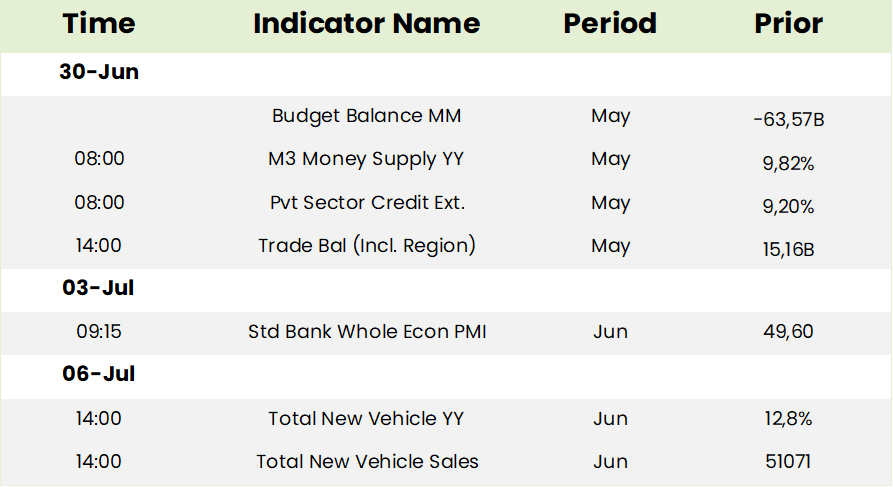
SA Upcoming Indicators & Dividends
*holding in a Finova portfolio
Trading Statements & Updates
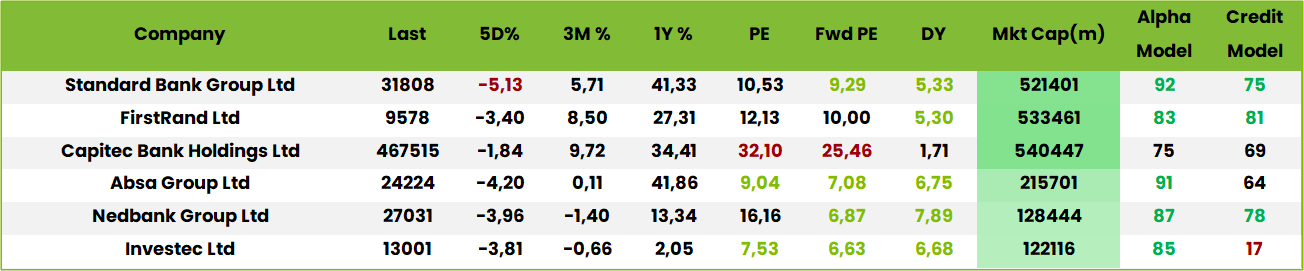
Standard Bank (SBK) Voluntary Trading Update for 5M to May ’26 (31808c)
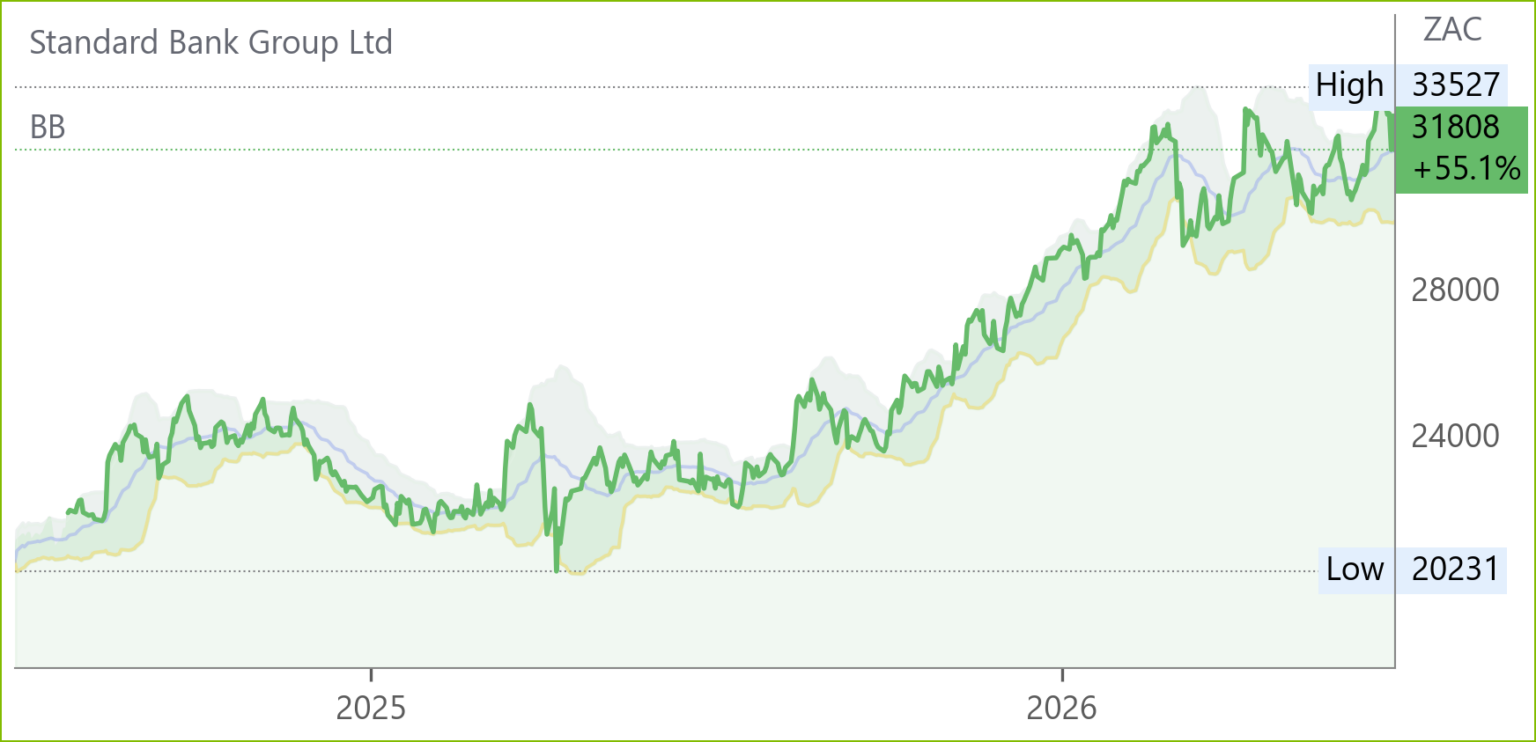
Balance sheet growth was driven by strong origination in Investment Banking and increased disbursements in Business and Commercial Banking, while current accounts and deposits showed robust expansion. Trading revenue benefited from volatility, and cost growth remained aligned with revenue. Credit impairment charges declined, lowering the credit loss ratio. Insurance & Asset Management earnings momentum continued, supported by persistency and asset growth in South Africa and Nigeria. CET1 ratio stood at 13.2% at Mar ’26. Outlook guidance for FY26 remains unchanged, with confidence expected to improve in H2 as geopolitical risks ease. Results due 13 Aug ’26.
Nedbank (NED)* Pre‑Close Investor Update H1 ’26 (27031c)
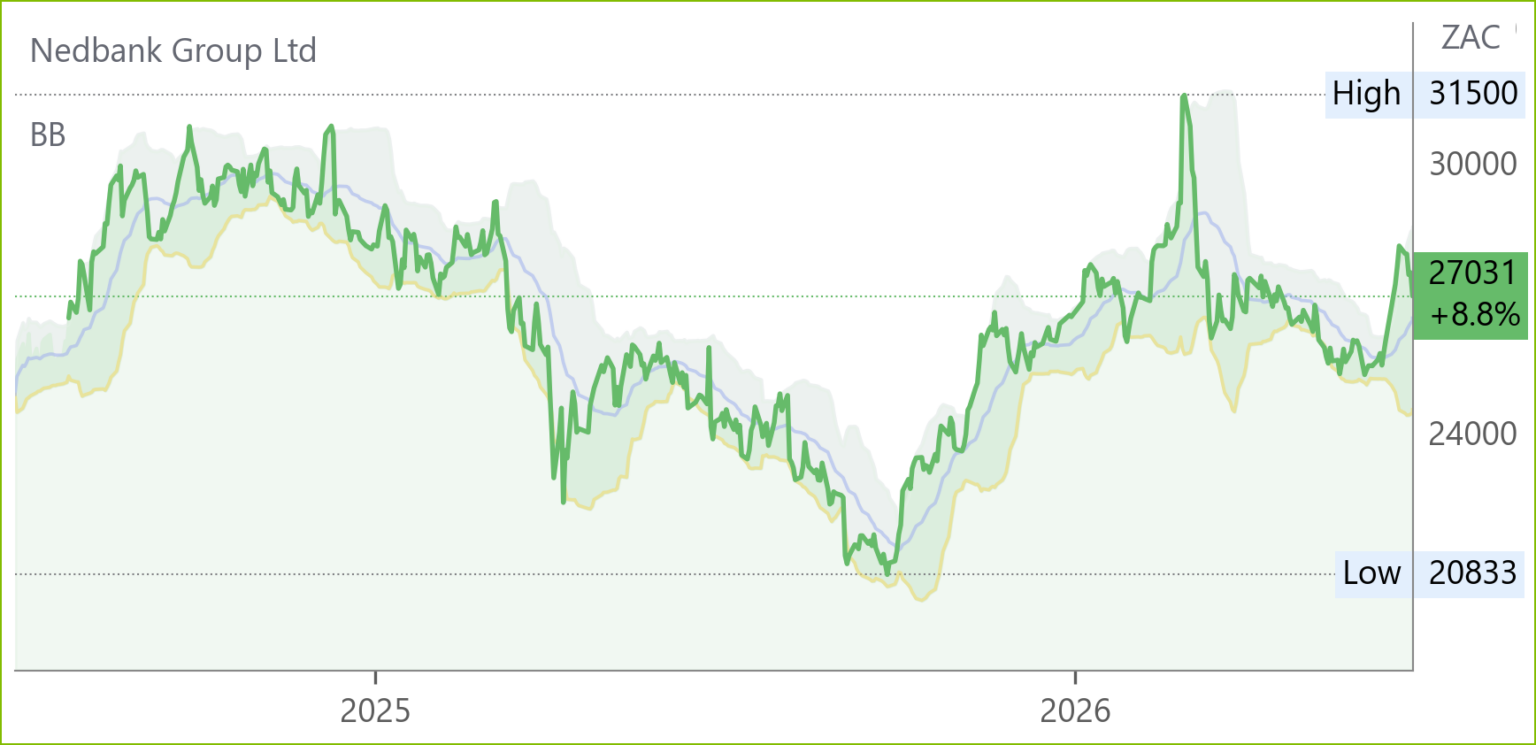
HEPS: Upper single‑digit growth (ex‑ETI)
EPS: Diluted EPS growth slightly ahead of HEPS due to 2025 buybacks
Operating Profit: Upper single‑digit PPOP growth (ex‑associates)
Revenue: NII low‑to‑mid single‑digit growth; NIR upper single‑digit growth
Dividend: Interim dividend guidance unchanged
Corporate & Investment Banking delivered strong balance‑sheet growth, fee income and trading gains, offset by slower property finance. Business & Commercial Banking was impacted by a once‑off client impairment but underlying loan growth and double‑digit NIR were robust. Personal & Private Banking earnings were constrained by lower endowment income and higher impairments, though insurance and fee momentum remained strong. SADC operations grew earnings off a low base. Expenses were tightly controlled, below mid‑single digits. Credit loss ratio rose into the upper half of the 60–100bps TTC range, seasonally higher in H1.
The NCBA transaction is progressing, with regulatory approvals largely secured and completion expected by end Q3 or early Q4 ’26. Results due 4 Aug ’26.
FirstRand (FSR)* Trading Update FY26 (9552c)
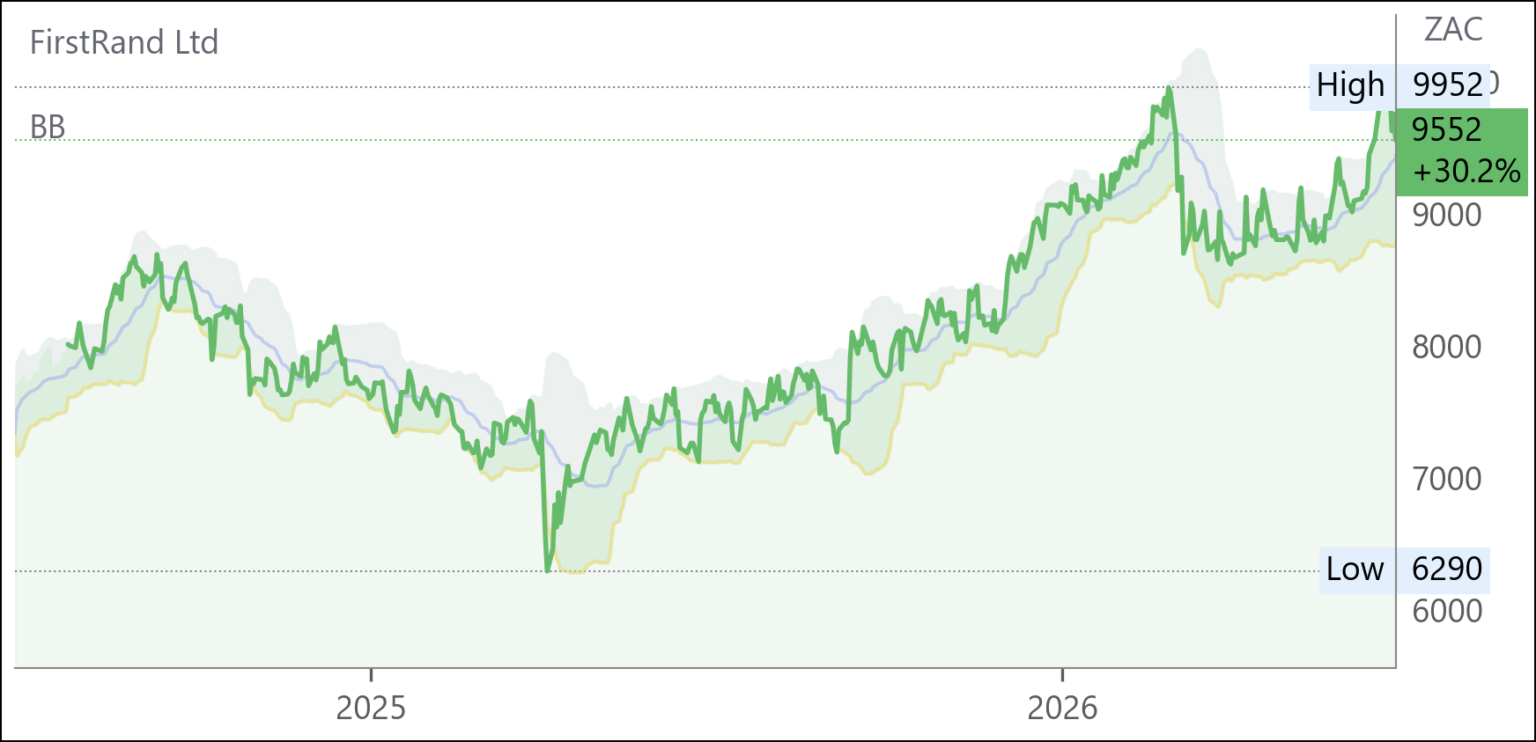
HEPS: Guidance contraction of 4–9% due to FCA UK motor commission provision
Operating Profit: Solid growth excluding UK provision impact
Revenue: Robust NIR growth from trading, investment income, and RMB fees
Dividend: Payable, calculated on earnings before UK provision impact
Advances growth accelerated in H2, driven by FNB retail, WesBank vehicle finance, and RMB corporate lending. Credit performance improved, with ratios at or below through‑the‑cycle ranges. UK operations will be disclosed as discontinued, with exit expected within 12 months, dampened by margin compression and offshoring costs. Stronger South African and broader Africa franchises offset UK weakness, supported by disciplined cost management and capital optimisation. Fiscal consolidation and structural reforms in South Africa provided macroeconomic anchors In South Africa, fiscal consolidation remains intact. Results due 10 Sep ’26.
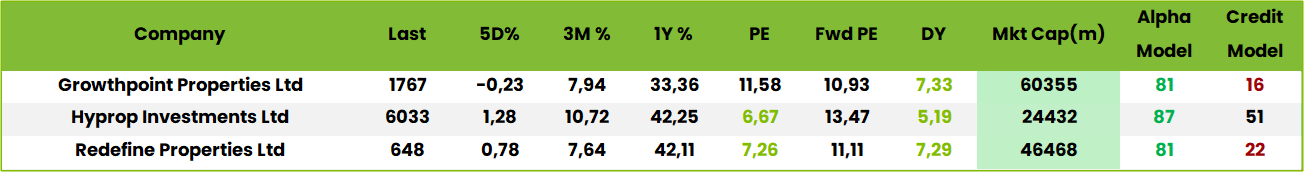
Growthpoint (GRT) Investor Update for 9M Mar ’26 (1767c)
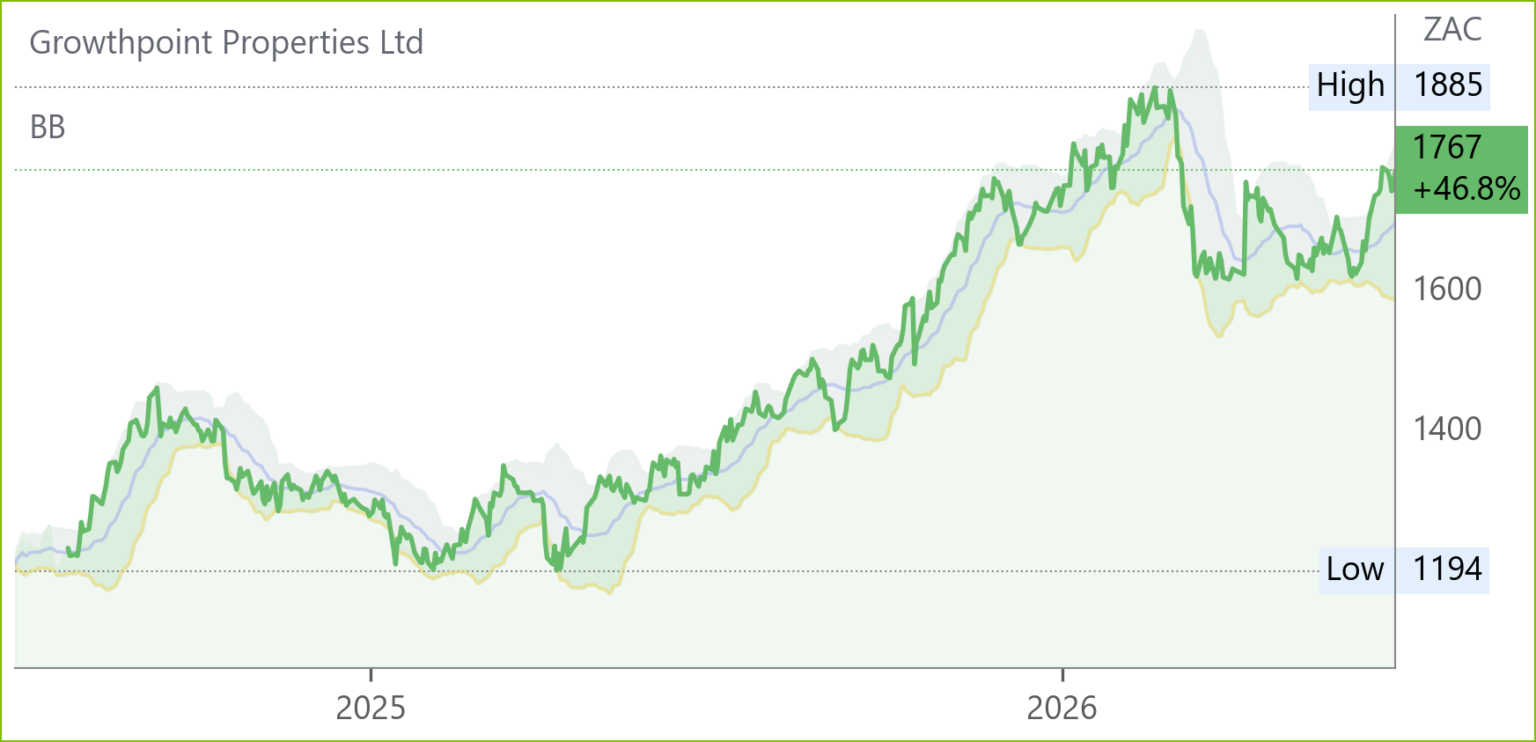
Disposals of R5.1bn exceeded the R3.5bn target, including the transfer of the Discovery building for R2.3bn. Vacancies improved to 7.3% from 8.2%, with renewal success rates rising to 79.1%, the highest in a decade. Overall vacancies improved from 8.2% at 30 June 2025 (FY25) to 7.3%.. Retail trading density grew 3.2% y/y, with footfall up 1.2%. Logistics vacancies fell to 2.8%, the lowest in over ten years. Vacancies improved from 4.1% at FY25 to 2.8%, the lowest level in more than a decade. Sustainability initiatives advanced, with rooftop solar PV capacity reaching 64.7MWp and renewable penetration at 17.9%. The V&A Waterfront delivered strong retail sales growth of 5.1% y/y, with footfall exceeding 2.4m visitors in Mar ’26. CEO Norbert Sasse noted that “our disciplined capital allocation and balance sheet strength underpin sustainable growth”. Results due 9 Sep ’26.
Hyprop (HYP) Operational Update for 5M May ’26 (6033c)
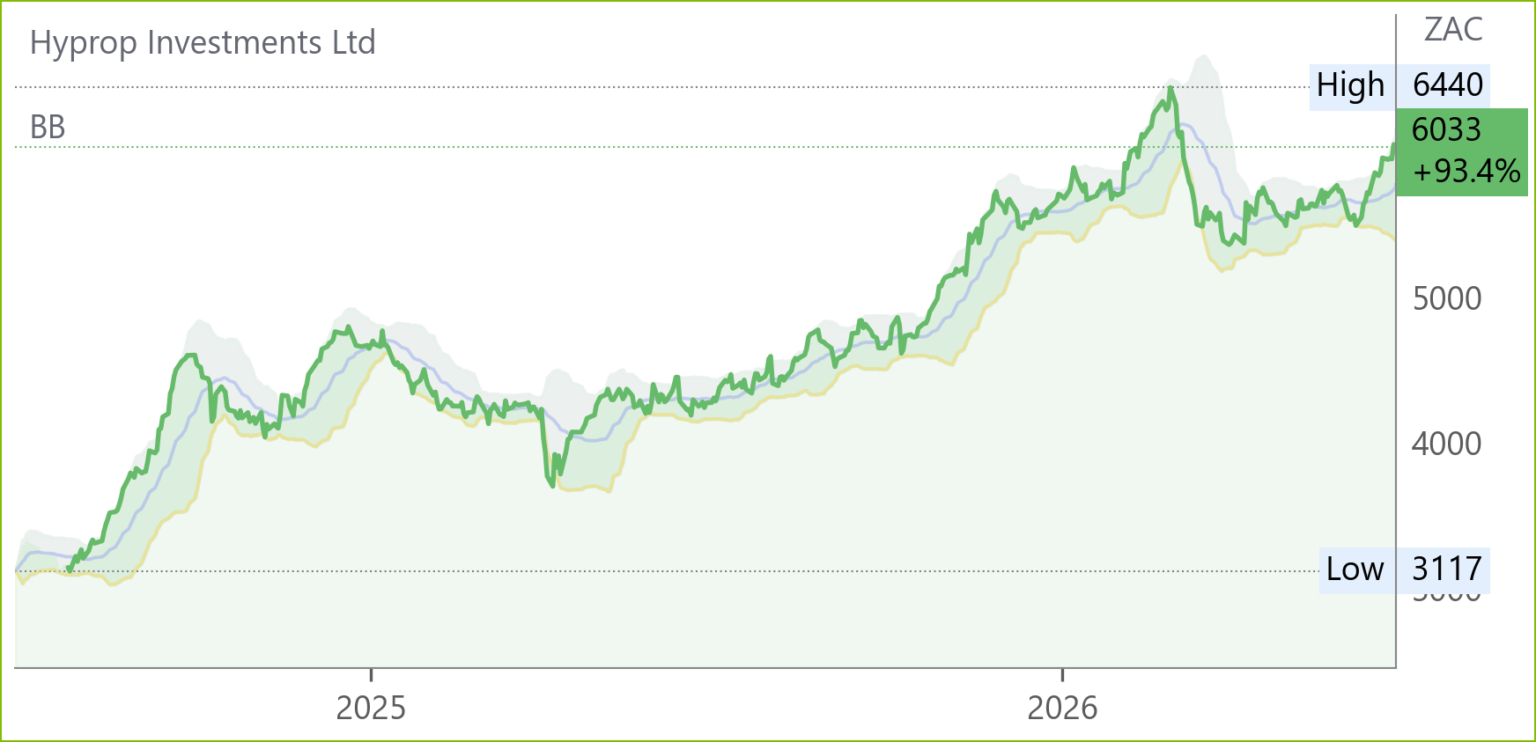
Dividend: Guidance for FY26 DPS growth of 10–12%
South African centres delivered turnover growth of 5.5%, trading density up 4.4%, and foot count rising 2.1%, with vacancies at just 3.3%. Cash collections strengthened to R1.7bn. Cash collections from tenants rose to R1.7 billion from R1.6 billion in 2025; Canal Walk, Somerset Mall, CapeGate and Table Bay Mall saw major tenant openings and refurbishments, enhancing retail mix. Gauteng assets added premium brands and upgraded infrastructure, while Rosebank Mall cut vacancies to 1.3%. Rosebank Mall has successfully reduced its vacancy rate from 2.0% to 1.3%.. Eastern Europe centres reported turnover growth of 4.4%, trading density up 4.2%, foot count up 5%, and zero vacancies. The Galleria Burgas acquisition in Bulgaria is set to complete by 31 Jul ’26, funded from disposals and cash reserves
Exxaro (EXX)* Finance Director’s Pre-Close Message 1H26 (20292c)
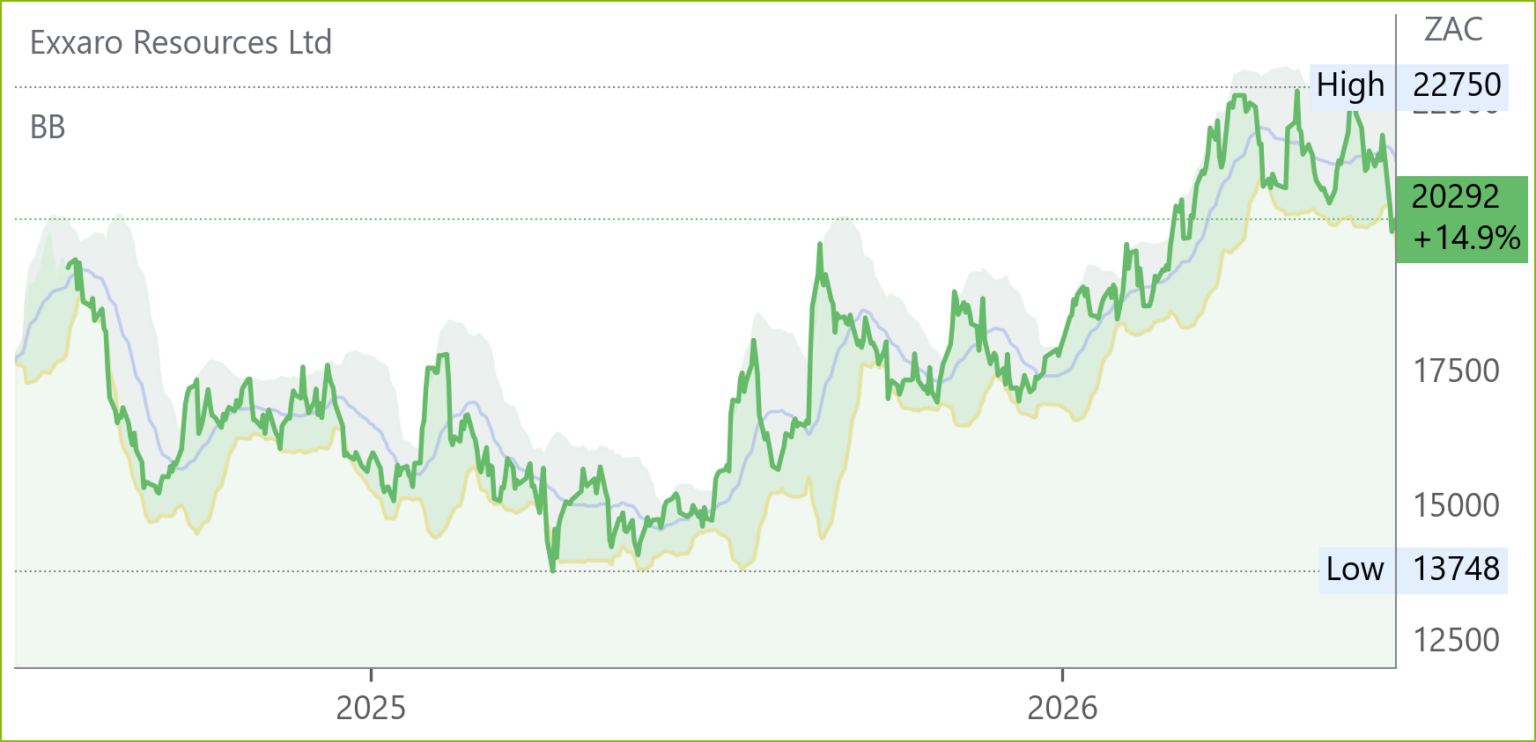
Coal production is forecast to rise 10% to 21.3Mt, with thermal coal up 8% and metallurgical coal surging 41%. Sales volumes are expected to increase 6%, driven by a 15% uplift in exports Commercial sales are expected to remain flat with Belfast capitalising on opportunities in the local market to alleviate…. Capital expenditure is projected 69% higher at R1.46bn, mainly at Grootegeluk and Belfast. Net cash stood at R6.6bn at May ’26, excluding R7.7bn net debt in energy operations. As of 31 May 2026, the group had net cash of R6.6 billion (excluding net debt of R7.7 billion in the energy business).. Renewable generation guidance is 830–860GWh, supported by the Lephalale Solar Project. Interim results due 20 Aug ’26.
Snippets
Pan African (PAN) secured conditional admission to the ASX, paving the way for a dual listing alongside the JSE and LSE. The Emmerson Resources acquisition remains subject to shareholder approval on 15 Jun ’26 and Australian Court sanction. Implementation is scheduled for 1 Jul ’26, with ASX trading commencing 2 Jul ’26. CEO Cobus Loots emphasised strategic growth through Emmerson’s assets, enhancing production and investor reach.
Optasia (OPA) confirmed that all Nigerian operators have resumed airtime credit services (ACS) following the temporary suspension earlier this year. Regulatory changes remain on hold pending ongoing legal proceedings. Restoration of ACS ensures millions of consumers regain access to essential connectivity. The company continues to monitor developments and will update shareholders as appropriate.