Finova Investor Digest
Global Indices
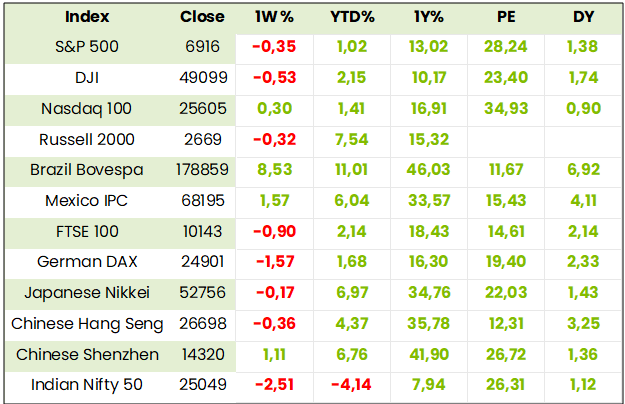
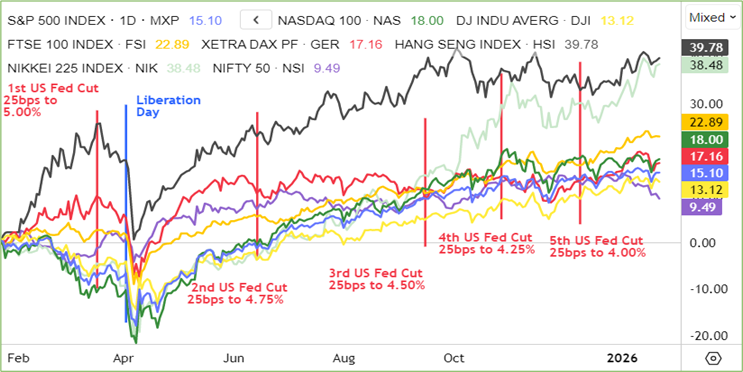
Global Indices 1 year to Date
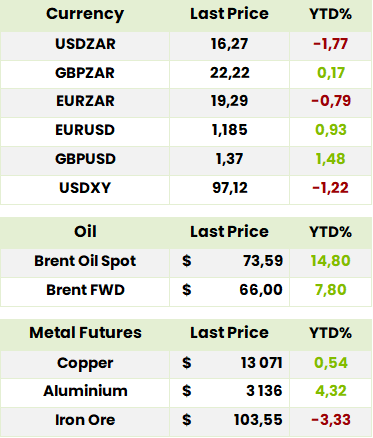
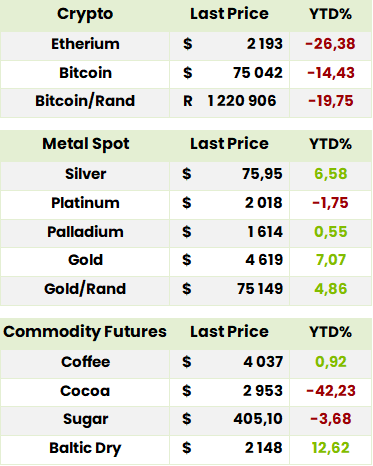
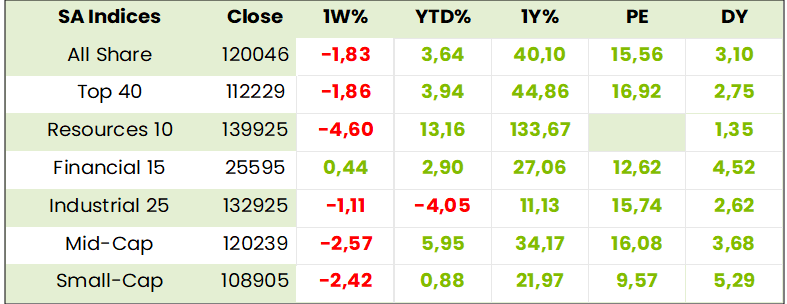
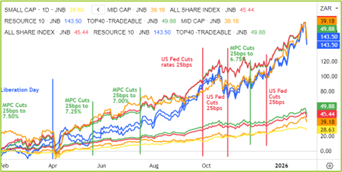
SA Indices
SA Upcoming Indicators & Dividends
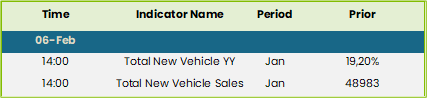
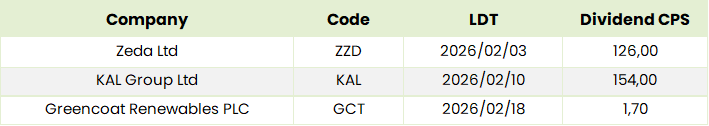
SA Equity
Operating Updates & Trading Statements
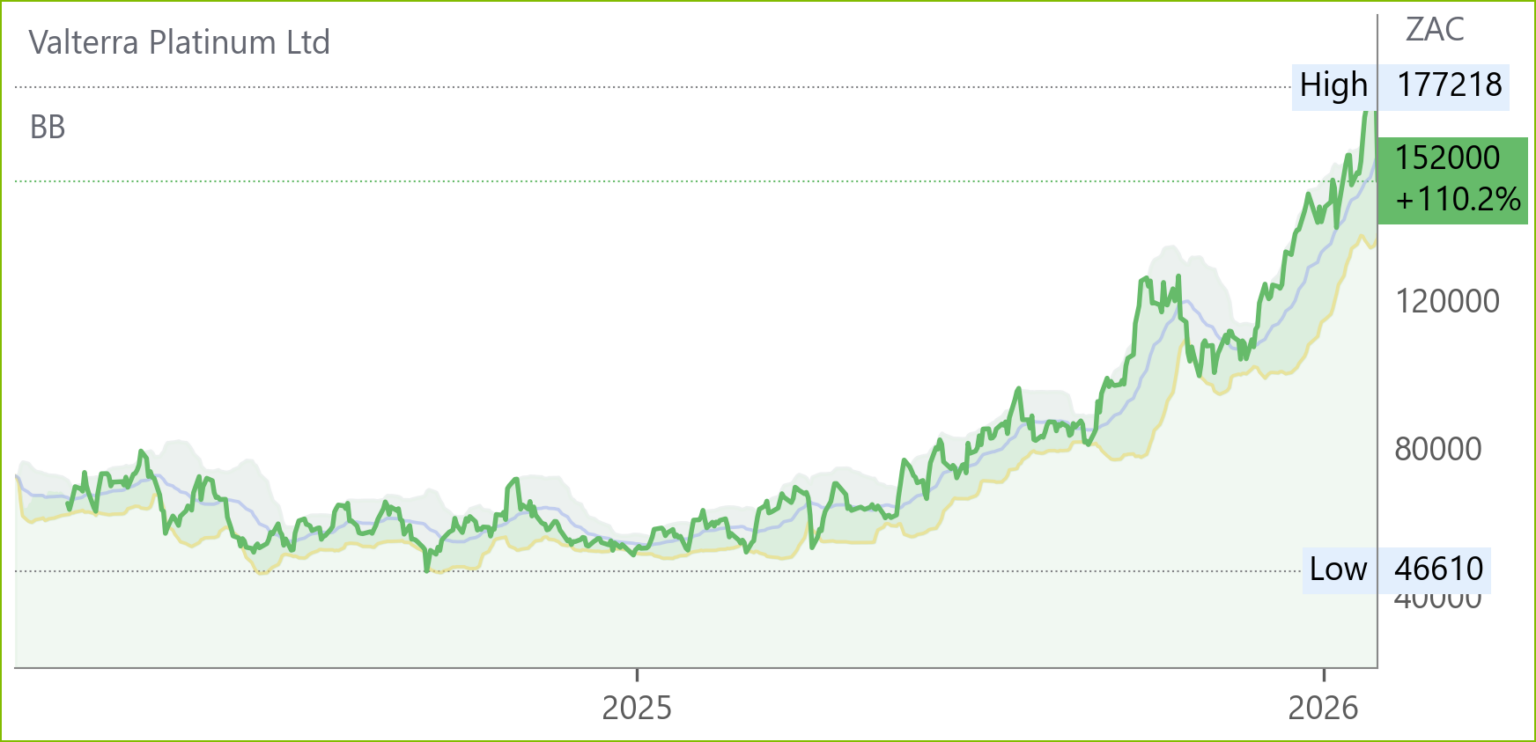
Valterra (VAL) Trading Statement FY25 (152000c)
HEPS: 5,941–6,588c (↑85–105% from 3,205c)
EPS: 5,522–6,055c (↑105–125% from 2,683c)
EPS rose faster than HEPS due to R1.9bn asset scrapping costs and insurance proceeds. Stronger PGM basket prices (+26%) and R5bn cost savings offset inflation and demerger costs. Flooding at Amandelbult Tumela mine reduced output, partly cushioned by R2.5bn insurance recovery.
Higher PGM prices and cost reductions drove earnings growth despite flooding at Amandelbult and one-off demerger costs. Asset scrapping linked to smelter and tailings redesign weighed on EPS, while insurance proceeds provided relief. Management emphasised sustainability and disciplined capital allocation, positioning Valterra as a standalone integrated PGM producer. Results due 25 Feb ‘26.
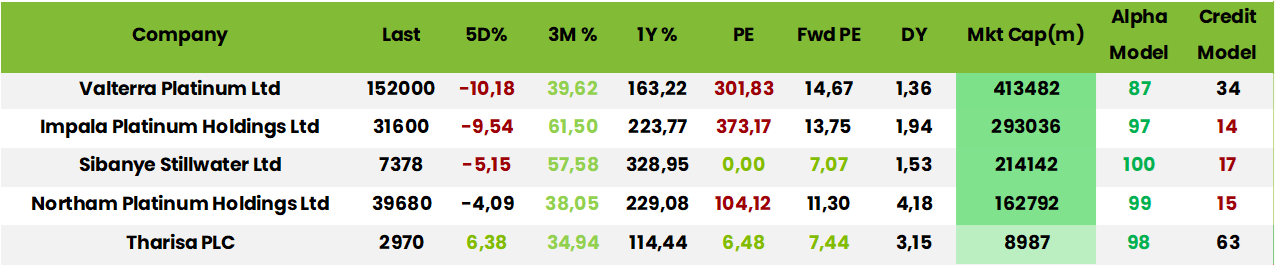
Comment: while, at 151453c, the mid-range of expected FY25 Heps points to a PE of 24.2x, the consensus FY26 HEPS FPE of 18.32x points to a 54% increase to 9643c but the market, not without reason is expecting much more. Since decoupling from Anglo American, Valterra has fulfilled expectations for cost savings and better focus which, together with top quality resources and surplus refining capacity, justify its premium rating.
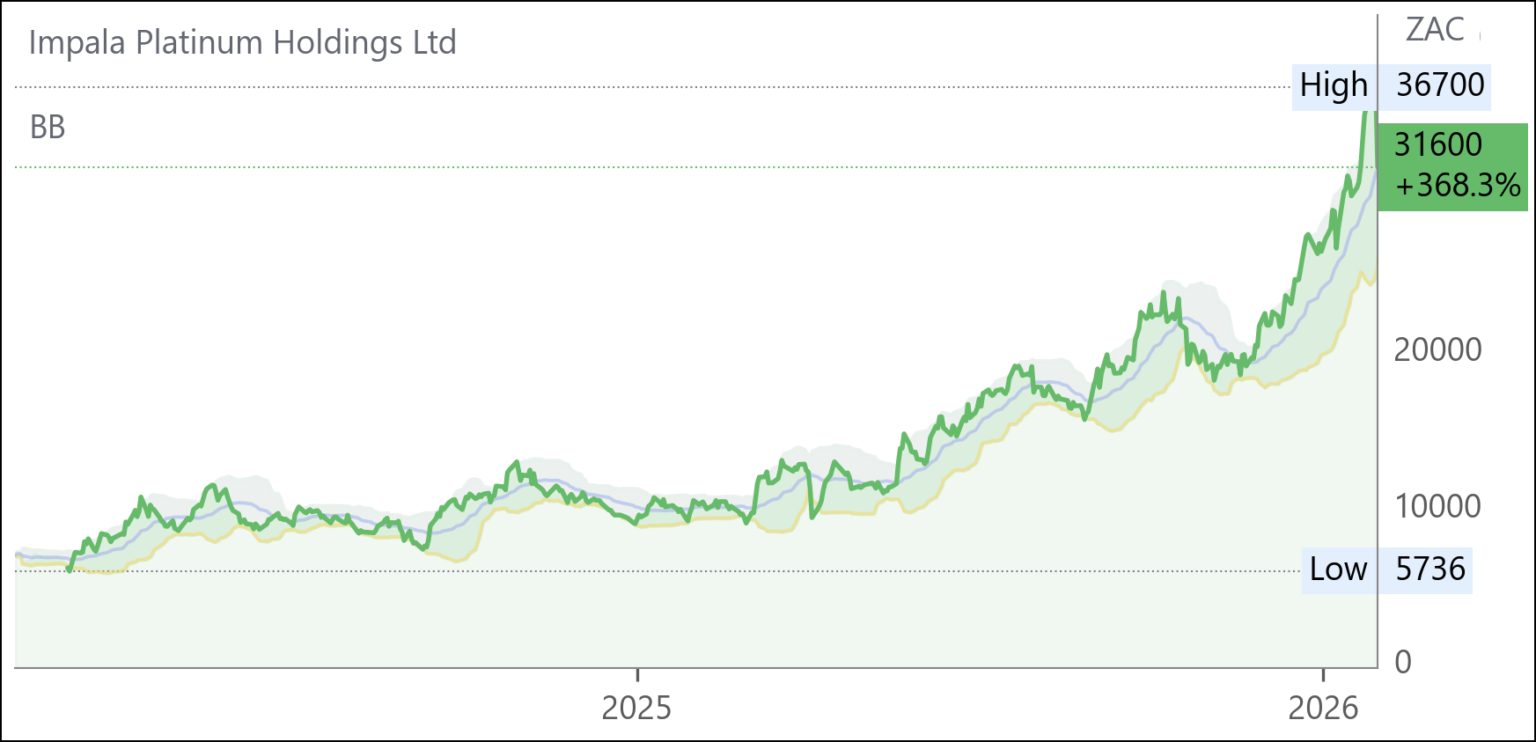
Impala (IMP) Production Update for 6M Dec 25 (31600c)
Operational resilience and efficiency improvements supported a commendable performance in H1 FY26, with notable gains in Q2. Management highlighted safe and consistent delivery across mining operations, despite ongoing cost pressures and global market volatility. Strategic initiatives in employee equity ownership, housing, and community investment continued to strengthen stakeholder trust. Outlook remains cautious but constructive, with management emphasising disciplined capital allocation and operational focus. “Our sustained focus on safe, consistent and efficient operational delivery underpins our ability to navigate a challenging environment.” – Nico Muller, CEO.
Results due 5 Mar ’26.
Comment: while the production performance was indeed commendable and prompted the board to declare an interim dividend of 125cps the share price has of course mainly reflected the massive surge in PGM prices as well as the, long overdue, correction on Friday. Upcoming sector results will better facilitate relative valuations but, in general, investment positions can be held. Currently we prefer Northam and, although we recently pointed to reasons as why Tharisa appeared to be so undervalued, the subsequent shift in PGM prices points to earlier revaluation ahead.
Pan African Resources (PAN) Operational Update H1 Dec 25 (2922c)
Dividend: Interim dividend proposed at 12cps
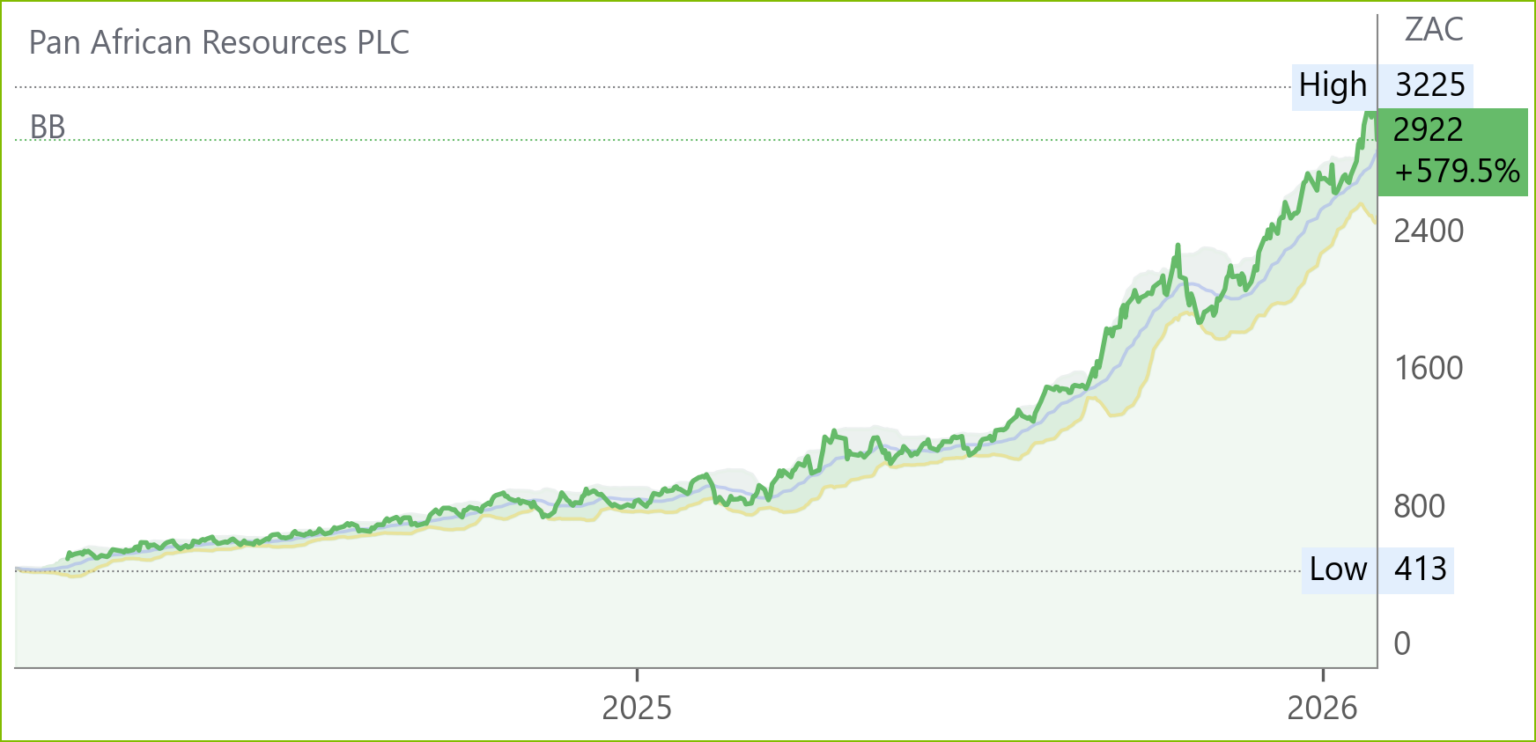
Gold production surged 51% to 128,296oz, driven by Evander (+87%) and Tennant Mines reaching steady state. Net debt reduced >65% to US$49.9m, with full de-gearing expected by Feb ’26.
Strong operational momentum in H1FY26 – gold output up 51% to 128,296oz – was supported by Evander’s turnaround and Tennant’s ramp-up. Balance sheet de-gearing exceeded 65%, positioning the Group for full debt elimination by Feb ’26 despite record dividend payments. ESG initiatives advanced, including solar expansion to 30MW and new water treatment plants. The Mogale Tailings expansion was commissioned, with Soweto Cluster feasibility due Jun ’26. “Pan African’s safety, operational and financial performance, together with record gold prices, has positioned us to deliver outstanding results for the full year.” – Cobus Loots, CEO. Results due 18 Feb ’26.
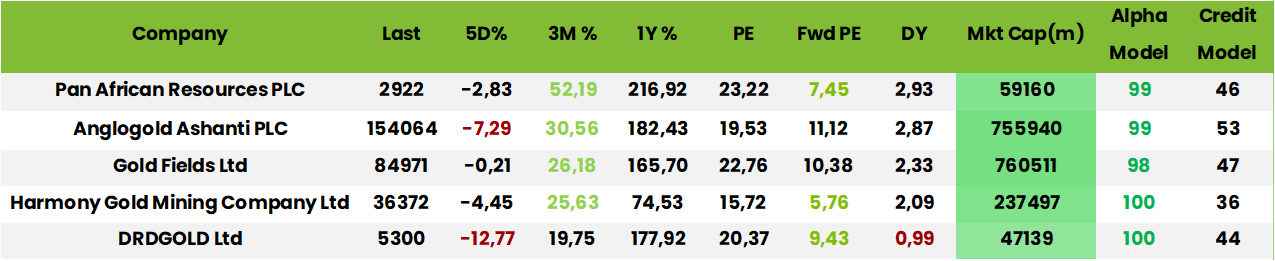
Comment: Panaf’s shoot the lights out result, including de-gearing, puts the stock into harvest mode with rising production after years of steady capex. Management could not, however, resist the temptation, to look to bring forward the Soweto Cluster instead of, after processing all the Mogale Tailings material after 15 years, merely connecting it with a 15km pipeline.
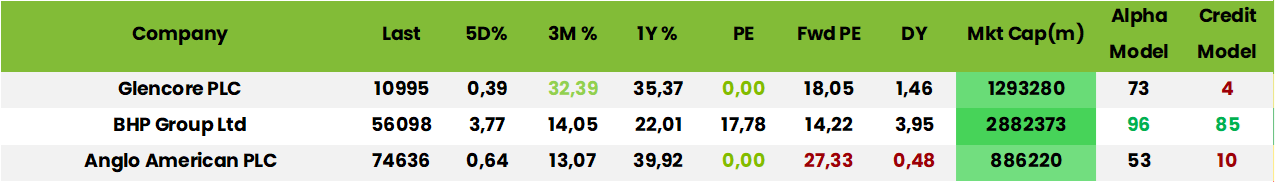
Glencore (GLN) Production Report FY25 (10995c)
EBITDA: Marketing Adjusted EBIT expected mid‑point of US$2.3–3.5bn guidance range
Copper output fell 11% YoY to 851.6kt due to lower grades and mine sequencing, while H2 copper surged 48% vs H1 on improved recoveries. Steelmaking coal rose 63% to 32.5Mt following Elk Valley acquisition.
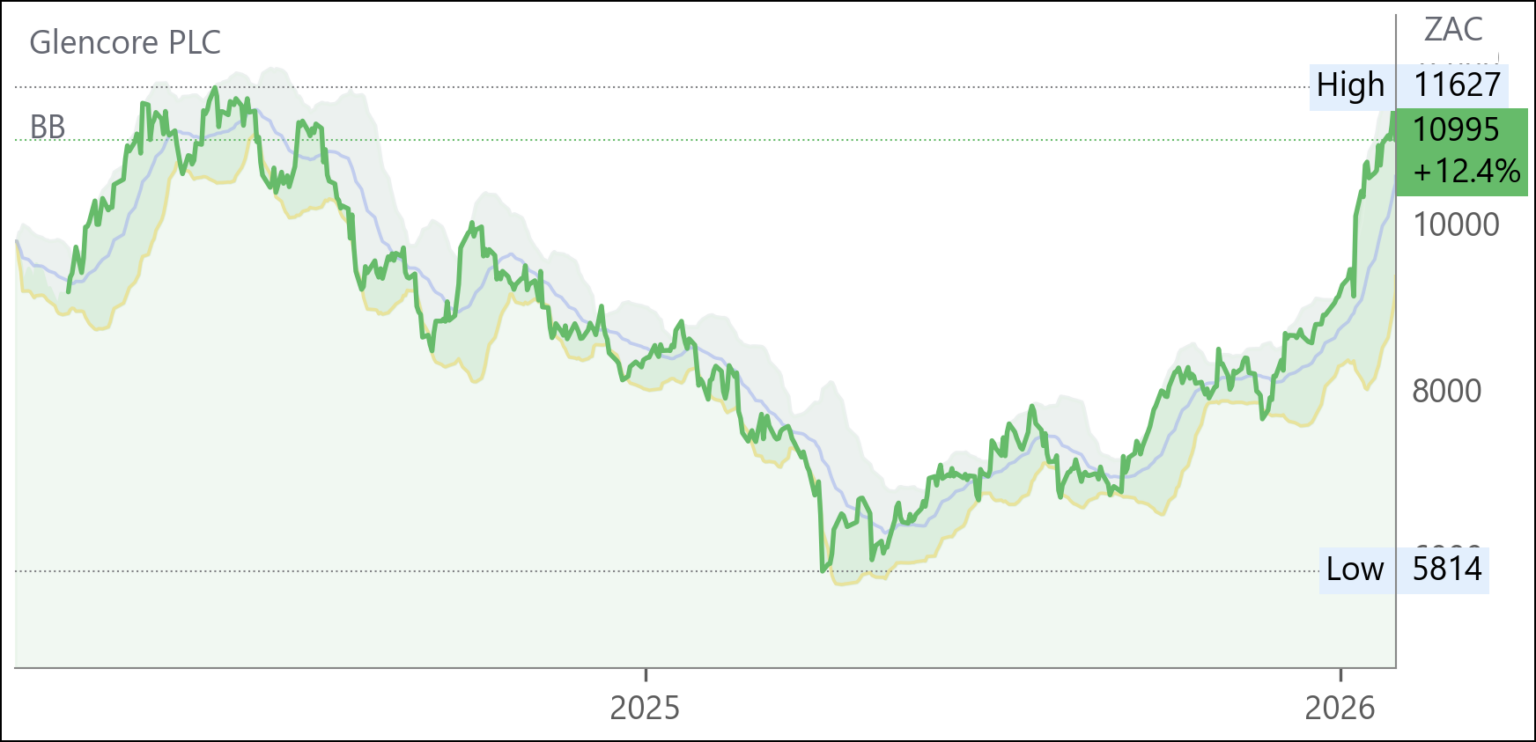
Glencore delivered FY25 production broadly within guidance, with copper 851.6kt (–11%), zinc 969.4kt (+7%), nickel 71.9kt (–13%), and cobalt 36.1kt (–5%). Steelmaking coal volumes jumped 63% to 32.5Mt, reflecting Elk Valley integration, while energy coal eased 2% to 98Mt. Silver rose 6% to 20.4Moz. CEO Gary Nagle highlighted expanded copper reserves at NewRange, Antapaccay, Lomas Bayas and El Pachón, positioning Glencore to become one of the world’s largest copper producers over the next decade. “We achieved production within guidance ranges, reflecting benefits of our optimised operating structures.”
Comment: Rio Tinto has until 5 February to decide whether or not to make a bid for Glencore which would result in the merged entity being the world’s biggest mining company. Glencore and Samancor both seem likely to benefit from Nersa’s granting permission for Eskom to reduce the electricity charges for their ferrochrome smelters
which otherwise were about to be closed.
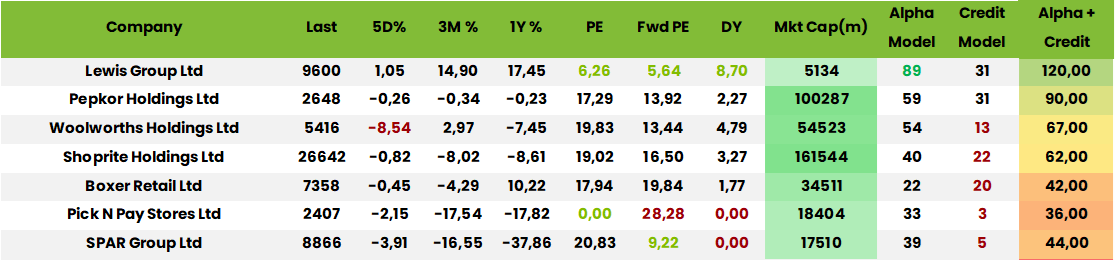
Lewis (LEW) Trading Update for 9M Dec 25 (9600c)
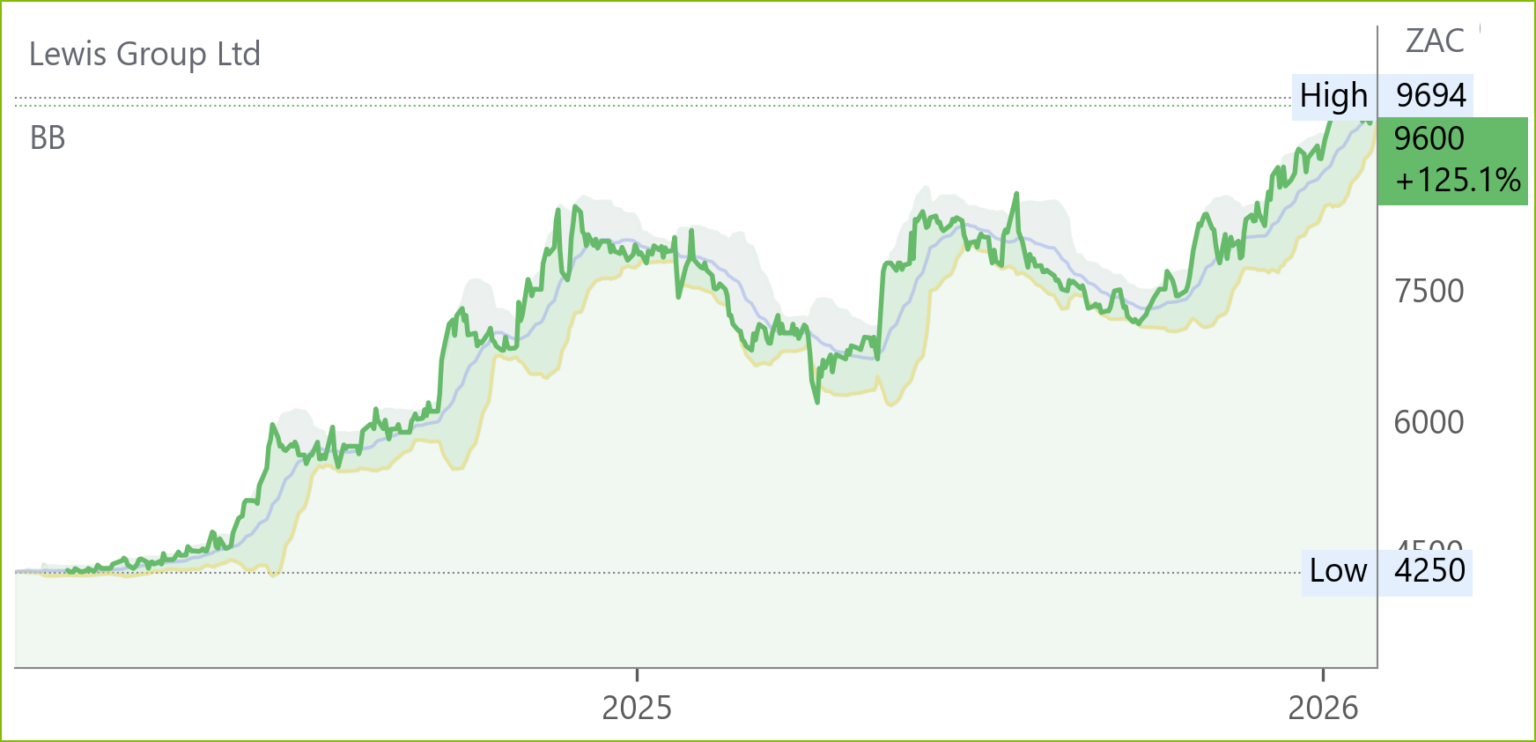
Revenue: ↑11.1% (driven by credit sales +9.1%)
Revenue growth was supported by credit sales rising to 69.4% of total sales, while cash sales grew modestly.
Lewis achieved 11.1% revenue growth for the nine months to Dec ’25, underpinned by strong credit sales and resilient Black Friday trading. Merchandise sales rose 7.1%, with comparable store sales up 4.3%. Other revenue, including insurance and ancillary services, increased 16.2%, reflecting the expanding debtors book. Collection rates remained steady at 78.3%, though debtor costs climbed 14.8% amid consumer pressure. Management highlighted robust brand performance and disciplined credit management as key strengths. “Our trading momentum demonstrates resilience in a challenging environment, with credit sales continuing to underpin growth.” – Johan Enslin, CEO. Results due 28 May ’26.
Comment: despite recent share price action the stock remains a Buy on a PE of around 6.0x. The Constitutional Court has upheld the right of Lewis to participate in the deliberations of the Competition Tribunal on the prosposed acquisition by Pepkor of the furniture business of Shoprite. Either way we do not believe this is the end of the world by any means for Lewis and might even enhance its position as “the only alternative” in the mass market.
Woolworths (WHL) Interim Results for 26W Dec ’25 (5416c)
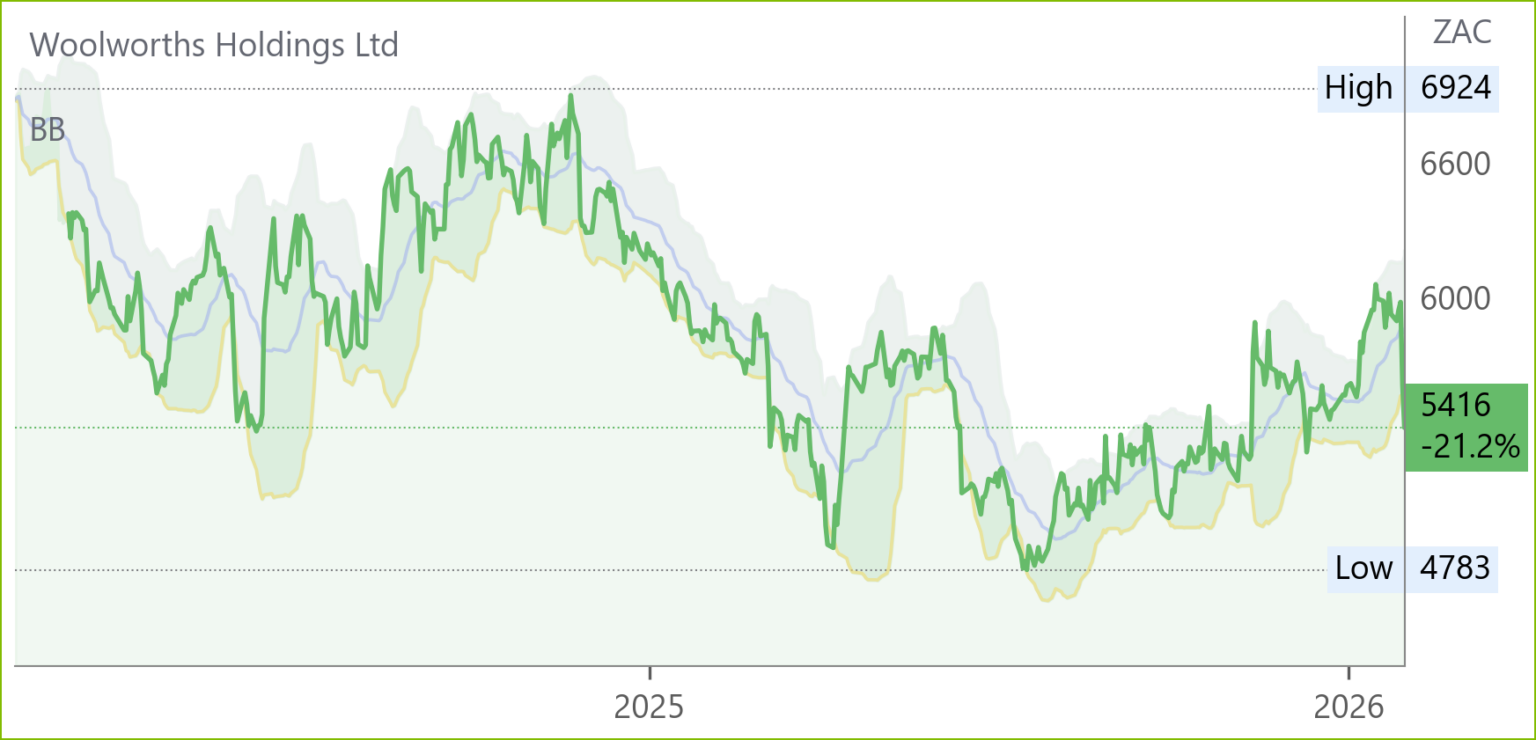
HEPS: 163.5–171.1c (↑7–12% from 152.8c)
EPS: 159.5–171.8c (↓30–35% from 245.4c)
Revenue: R8.88bn (↑5.4% from R8.47bn)
Gross Profit: Margin impacted by DC expansion and FBH clearance activity
EPS fell due to the prior year’s Bourke Street property sale base effect, while HEPS rose on stronger trading performance.
Turnover grew 5.4% with Food up 7% and Fashion, Beauty & Home up 6.2%, supported by improved supply chain and festive trading. Online sales expanded, with Woolies Dash up 23% and digital channels contributing 7.2% of Food and 6.2% of FBH sales. Country Road Group delivered 2.3% growth, though December trading softened. Financial Services grew 1.8% with sector‑leading impairment rates. “Our improved profitability reflects disciplined execution and resilience across core categories.” – Roy Bagattini, CEO. Results due 4 Mar ’26.
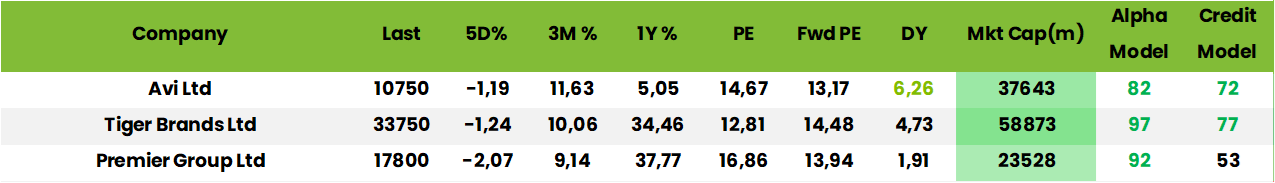
AVI (AVI) Trading Statement for 6M Dec 25 (10750c)
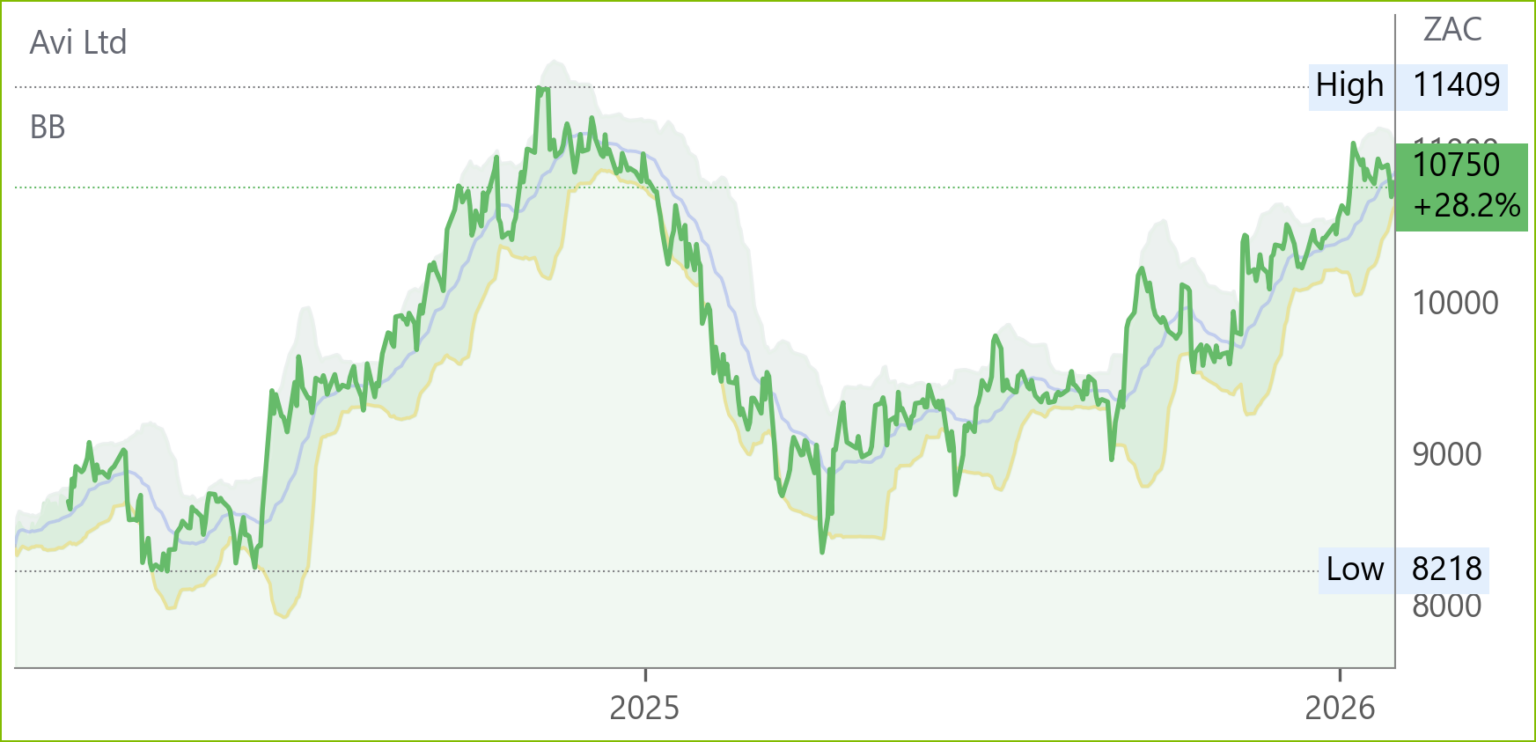
HEPS: 450.3–458.4c (↑10.5–12.5% from 407.5c)
EPS: 450.4–458.6c (↑9.5–11.5% from 411.3c)
Operating Profit: ↑ (margin improved, supported by I&J and cost containment)
Revenue: R8.88bn (↑4.9% from R8.47bn)
Gross Profit: ↑ (margin improved YoY)
HEPS and EPS growth broadly aligned. Revenue rose 4.9% with strong contributions from I&J (+9.4%) and Snackworks (+5.9%), offset by weakness in Personal Care (–7.2%).
AVI delivered resilient performance in H1FY26, with headline earnings up double digits despite a challenging consumer environment. Tea brands Freshpak and Five Roses grew volumes, while Bakers biscuits performed strongly over the festive season. I&J benefited from improved catch rates and new vessel capacity, though abalone sales remained pressured by oversupply in Asia. Indigo faced declining deodorant demand but launched innovations to stabilise volumes. SPITZ footwear recovered after prior supply issues, while apparel remained competitive. Cost discipline and prior restructuring supported margin expansion. “Our improved profitability reflects disciplined execution and resilience across core categories.” – CEO commentary. Results due 9 Mar ’26.
Cashbuild (CSB) Operational Update for Q2 FY26 (14500c)
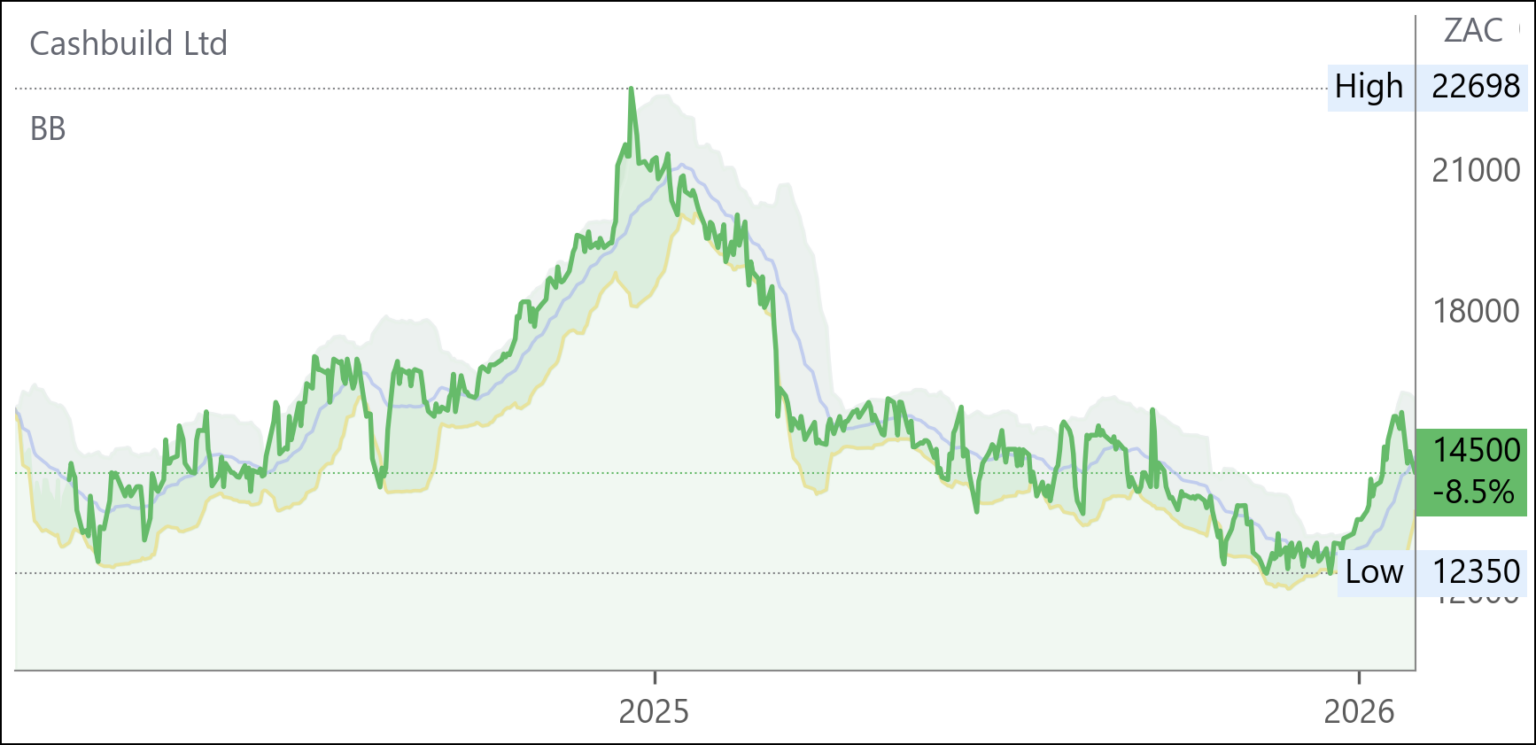
Revenue: ↑1% in Q2 FY26 (HY ↑3% vs HY25)
Explanation: Revenue growth was modest, with existing stores down 2% but new stores adding 3%. HY revenue rose 3% overall, supported by acquisitions and store expansion.
Cashbuild delivered a 1% revenue increase in Q2 FY26, with half-year growth of 3% despite weaker performance at existing stores. New outlets and the acquisition of Amper Alles contributed positively, while Malawi operations were disposed of. Store footprint reached 322 after openings, refurbishments, relocations, and closures. Transactions rose 2% in Q2 (HY ↑4%), reflecting resilient demand amid low selling inflation of 0.8%. Management highlighted disciplined expansion and operational efficiency as key priorities. “We remain focused on enhancing our store base and delivering sustainable growth for shareholders.” – Werner de Jager, CEO.

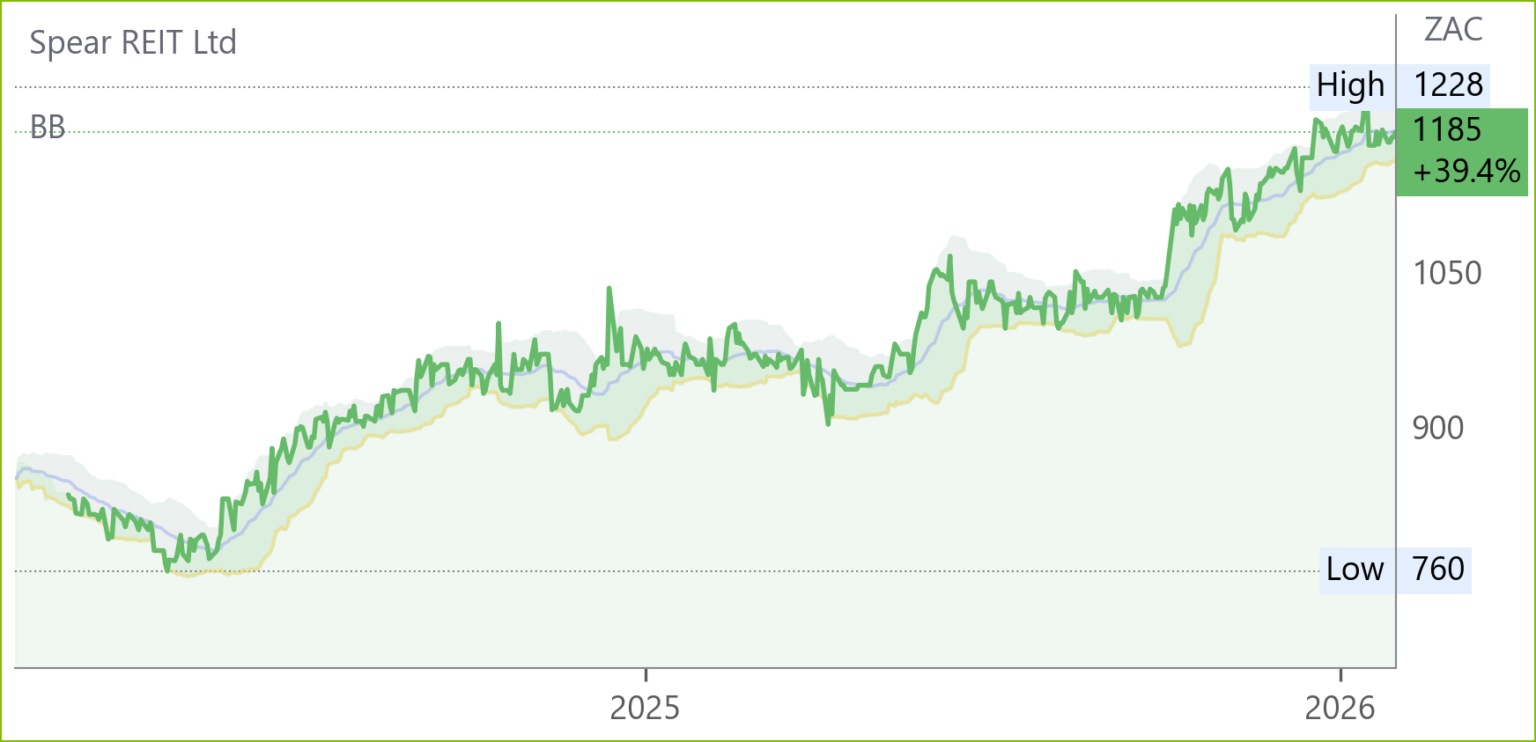
Spear (SEA) Operational & Financial Update 10M Dec 25 FY26 (1185c)
HEPS: 74.94c (↑2.8% from 72.92c)
EPS: 103.80c (↑32.1% from 78.59c)
Revenue: R674.5m (↑21.6% from R554.7m)
Distribution: 71.14cps (↑5.7% from 67.29cps, payout ratio 95%)
LTV: 25.04% (↓2.05pp from 27.09%)
EPS rose faster than HEPS due to asset revaluations and acquisitions. Revenue growth >20% reflects new property additions and strong industrial demand. Spear expanded its Western Cape-focused portfolio to 42 properties worth R6.8bn, adding Maynard Mall and 137,090m² of yield-enhancing assets. Industrial assets remain the cornerstone, supported by new developments in George and Blackheath. Vacancies fell to 2.84%, the lowest since COVID-19, while solar income grew with expanded capacity. Management revised FY26 distributable income guidance upward to 5–6% growth, citing robust letting momentum, improved debt costs, and supportive macro conditions. “Our improved financial cadence is a testament to the wholesale buy-in and execution of our operational and asset growth strategies by the entire Spear team.” – Izak Petersen, CEO. Comment: management is at pains to point to the 5.71% growth in distributable income to 74.88cps as being the comparable number while the current 13.0x PE and 7% DY compares favourably with the other sector leaders. The stock remains well rated as befits the only sector player to be wholly focused on the Western Cape.

Snippets
Vukile’s (VKE) subsidiary Castellana will sell its Spanish retail park portfolio to Ferrel SPV 2025, owned by Ares Management, for €279m effective 1 April 2026. The disposal crystallises a 13% NAV gain since 2017 and a 7.1% yield. Proceeds will be redeployed into higher‑growth shopping centres, while Castellana retains a five‑year asset management mandate.
Exxaro (EXX) confirmed its acquisition of key manganese assets from Ntsimbintle Holdings and OMH Mauritius, including full ownership of Ntsimbintle Mining (50.1% of Tshipi Borwa Mine), stakes in Jupiter, Hotazel, and Ntsimbintle Marketing. The deal is unconditional, closing by Feb ’26, while the Mokala transaction remains pending until Feb ’27. This diversifies Exxaro beyond coal into manganese growth.